
Welcome to The S-Curve
Now you will be able to receive the latest announcements, product updates, and our insights on the mortgage market in real time.
The name of the blog, the S-Curve, is a reflection of our logo and the central feature of our prepayment model. S-curves are seen in nature in many phenomenon, from population growth to prepayment and default models. Our first S-curve, in the early 1990s, used the arctangent function, then piece-wise linear functions, and evolved over time to be more complex and vary by FICO, loan size and LTV. This evolution encapsulates both the timeless nature of fundamental relationships and constant innovation to describe them better over time.
We hope you find the information useful and we look forward to your feedback.
-
 Real World Data on House Price Impact of Climate RisksThoughts
The earliest paper we found examining the impact of climate risks on house prices was from 2017, which found a relationship between elevation/sea level rise and house price differences.[1]
We built our climate-conditioned HPA model in 2022 based on the idea that an increase in insurance costs would impact house prices (something we had not studied yet) in the same way that an increase of the same size in mortgage rates would impact house prices (something that we were quite familiar with).
The real world evidence for this relationship has been accumulating recently – on October 15, 2024 the Washington Post published an article entitled “Where climate change poses the most and least risk to American homeowners” which contains the following chart (which is based on an analysis of 2 million home sales in Florida since 2000):
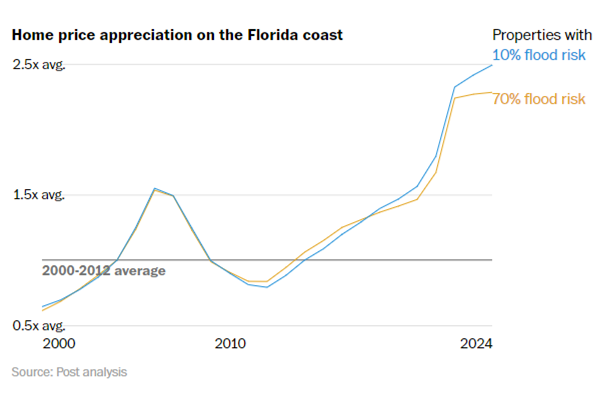
We can see from the lines comparing lower and higher flood risk properties that until very recently, the housing market was not pricing for flood risk. But now there is a clear divergence in price trend.
For the particular case of Florida, there is reason to believe that this trend will strengthen in the near term: until recently, the only reason most people got flood insurance was that they were in a FEMA flood zone and they were required to buy a NFIP policy in order to obtain a mortgage. FEMA flood zone maps are known to be extremely outdated. However, with the accumulation of flooding incidents occurring outside those zones and the publishing of flood risk scores on Zillow, buyers are becoming much more aware of flood risk whether or not a property is in a FEMA zone.
Additionally, the state of Florida is gradually requiring all homeowners buying insurance through Citizens (its FAIR plan for homeowner’s insurance) to also have flood insurance regardless of flood zone status. This requirement started in 2024 for houses priced $600,000 and above, and by January 1, 2027, will extend to all properties insured by Citizens. At the end of 2023, Citizens was the largest insurer in Florida with 15% of all policies and over half a trillion dollars of insured properties.
Furthermore, the different post-event experiences of homeowners who have flood insurance versus those who didn’t is likely to encourage more homeowners – even those not taking a policy through Citizens – to add flood insurance to their property. So flood risk, at least in Florida, is getting closer to being fully priced into real estate values.
While the Washington Post article only discusses flood risk, all borrower costs matter to housing affordability – property taxes, homeowner’s and flood insurance, and the mortgage (leaving aside the psychological costs of nuisance events that don’t rise to the level of filing a claim). To truly capture the potential impact on both house prices and borrower behavior of all these rising costs, a fully climate conditioned approach, combining home prices as well as borrower behavior models (how will prepayment, delinquency, default and loss severity be affected?) is required. This is what our Climate Impact Suite offers.
[1] https://papers.ssrn.com/sol3/papers.cfm?abstract_id=3073842&itid=lk_inline_enhanced-template
-
 AD&Co Welcomes New Third-Party Vendor: Mortgage Capital Trading, Inc. (MCT®)News
Andrew Davidson & Co., Inc (AD&Co) is pleased to announce a new alliance with Mortgage Capital Trading, Inc. (MCT), a leading provider of mortgage capital market solutions.
MCT’s mortgage servicing rights valuation model, MSRlive!, now supports AD&Co’s Agency, Agency+, Non-Agency and Multifamily LoanDynamics Model (LDM), providing clients with forecasts of prepayments, defaults and loss given defaults on agency pools and whole loans, as well as non-agency and multifamily loans and securities, respectively.
Valuation tools are vital to making investment decisions and MSRlive! provides MSR portfolio managers and mortgage bankers with the tools necessary to manage their MSR investments. Coupled with AD&Co’s LDM, clients can now access to a multi-model framework when building and managing their MSR portfolios.
AD&Co would like to thank MCT for their dedication to offering LDM through the MSRlive! platform and servicing our mutual clients to ensure their success.
Are you interested in learning more about accessing LDM via the MSRlive! platform? Please contact Bill Shirreffs at bshirreffs@mctrade.net.
-
 Empowering Our Community: AD&Co's Commitment to DEI and Social ImpactEvents
At Andrew Davidson & Co., Inc. (AD&Co), our dedication to Diversity, Equity, and Inclusion (DEI) has been a cornerstone of our values. We established our DEI Committee in 2020, following the tragic murder of George Floyd. Despite the evolving landscape, including the recent U.S. Supreme Court decision impacting affirmative action in higher education, we remain steadfast in our commitment to fostering an inclusive environment that strengthens both our employees and the company.
On August 15, we came together at our New York office for a meaningful community service project. Partnering with Volunteers of America® Greater New York's Operation Backpack®, our team assembled and distributed backpacks filled with essential school supplies for unhoused students across New York City. These backpacks, which serve elementary, middle, and high school students, included a personal touch: handwritten notes wishing each student a successful school year. We believe every child deserves access to the resources they need to thrive, and we're honored to contribute to easing their transition into a new school year.
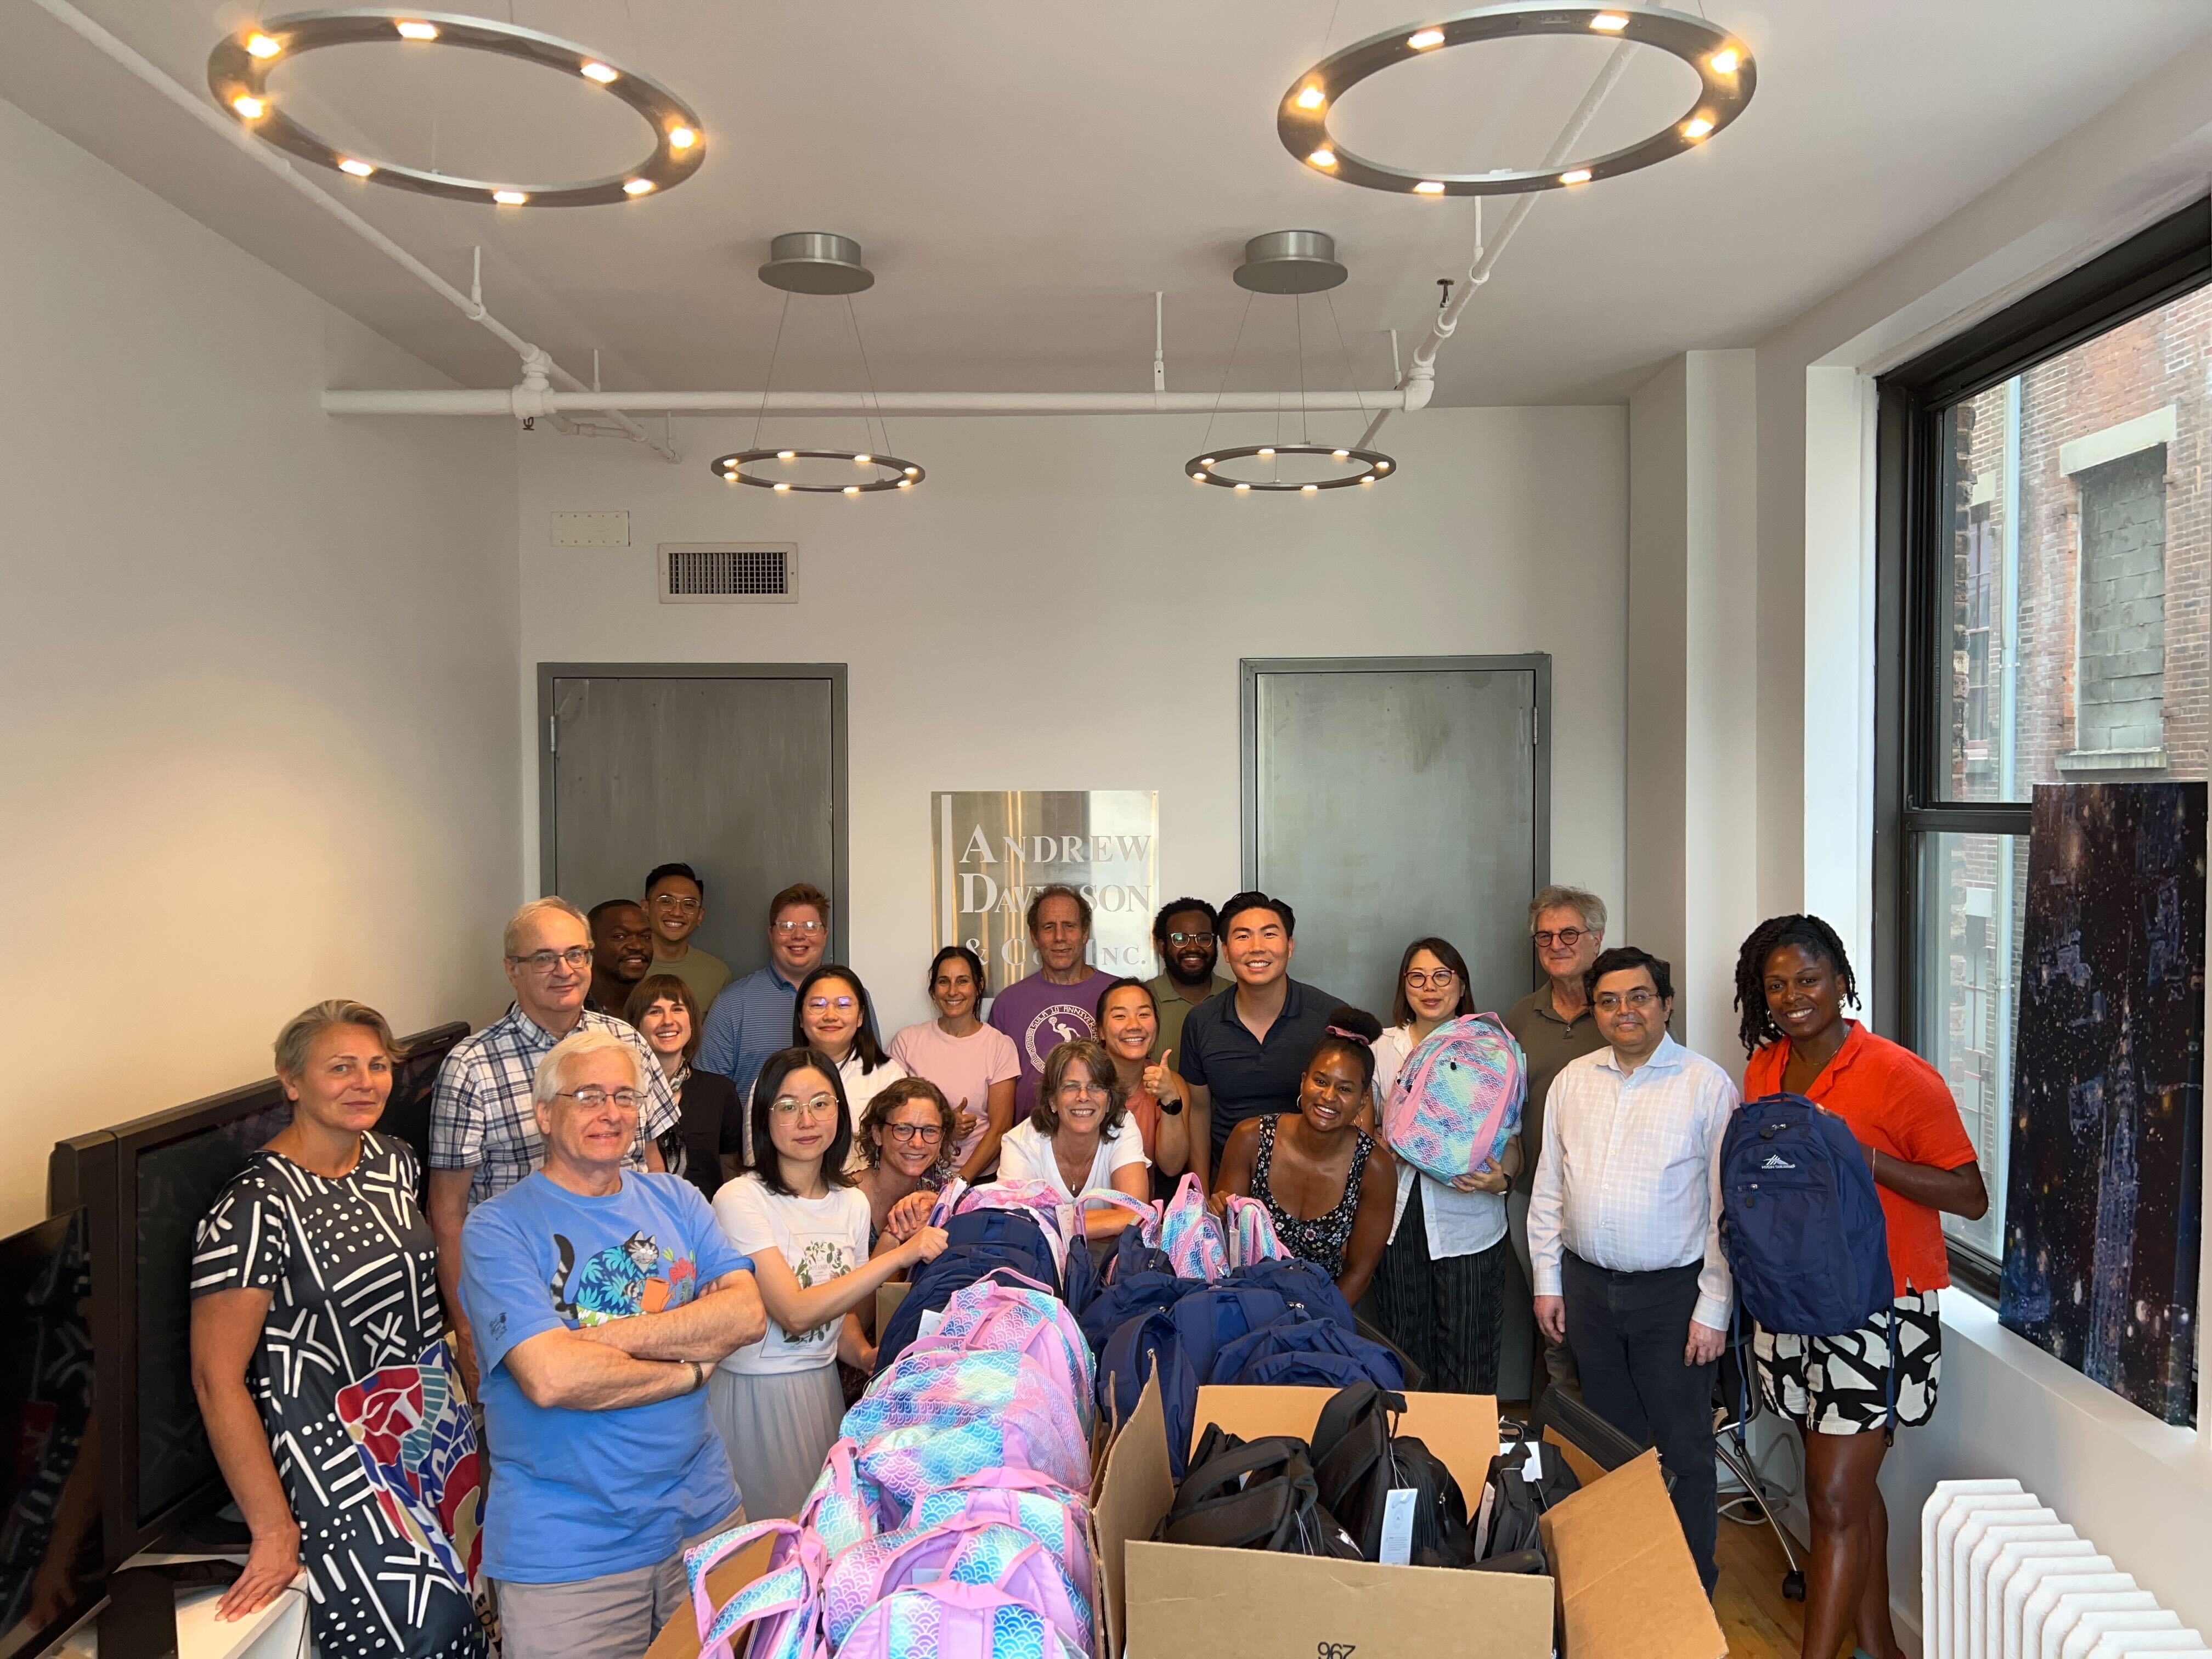
AD&Co team assembled to fill backpacks with essential school supplies for unhoused and underprivileged children. Later that day, our team participated in the "Other Side of Wall St." walk led by Kamau Ware of Black Gotham Experience. The walk began with a naming ceremony introducing members of North America's first Free Black Settlement. As we explored the historical impact of these early settlers on New York City, we were struck by the absence of formal recognition for their contributions in the city's landmarks. Kamau's insightful stories and imagery brought to light the rich yet often overlooked layers of history, reminding us of the importance of acknowledging and celebrating all aspects of our past. As a Black woman in mortgage finance, I take pride in working for a firm like AD&Co, which not only supports but actively promotes the values of diversity, equity, and inclusion. Our ongoing efforts are a testament to our commitment to elevating our employees, enhancing our business, and advancing our industry.
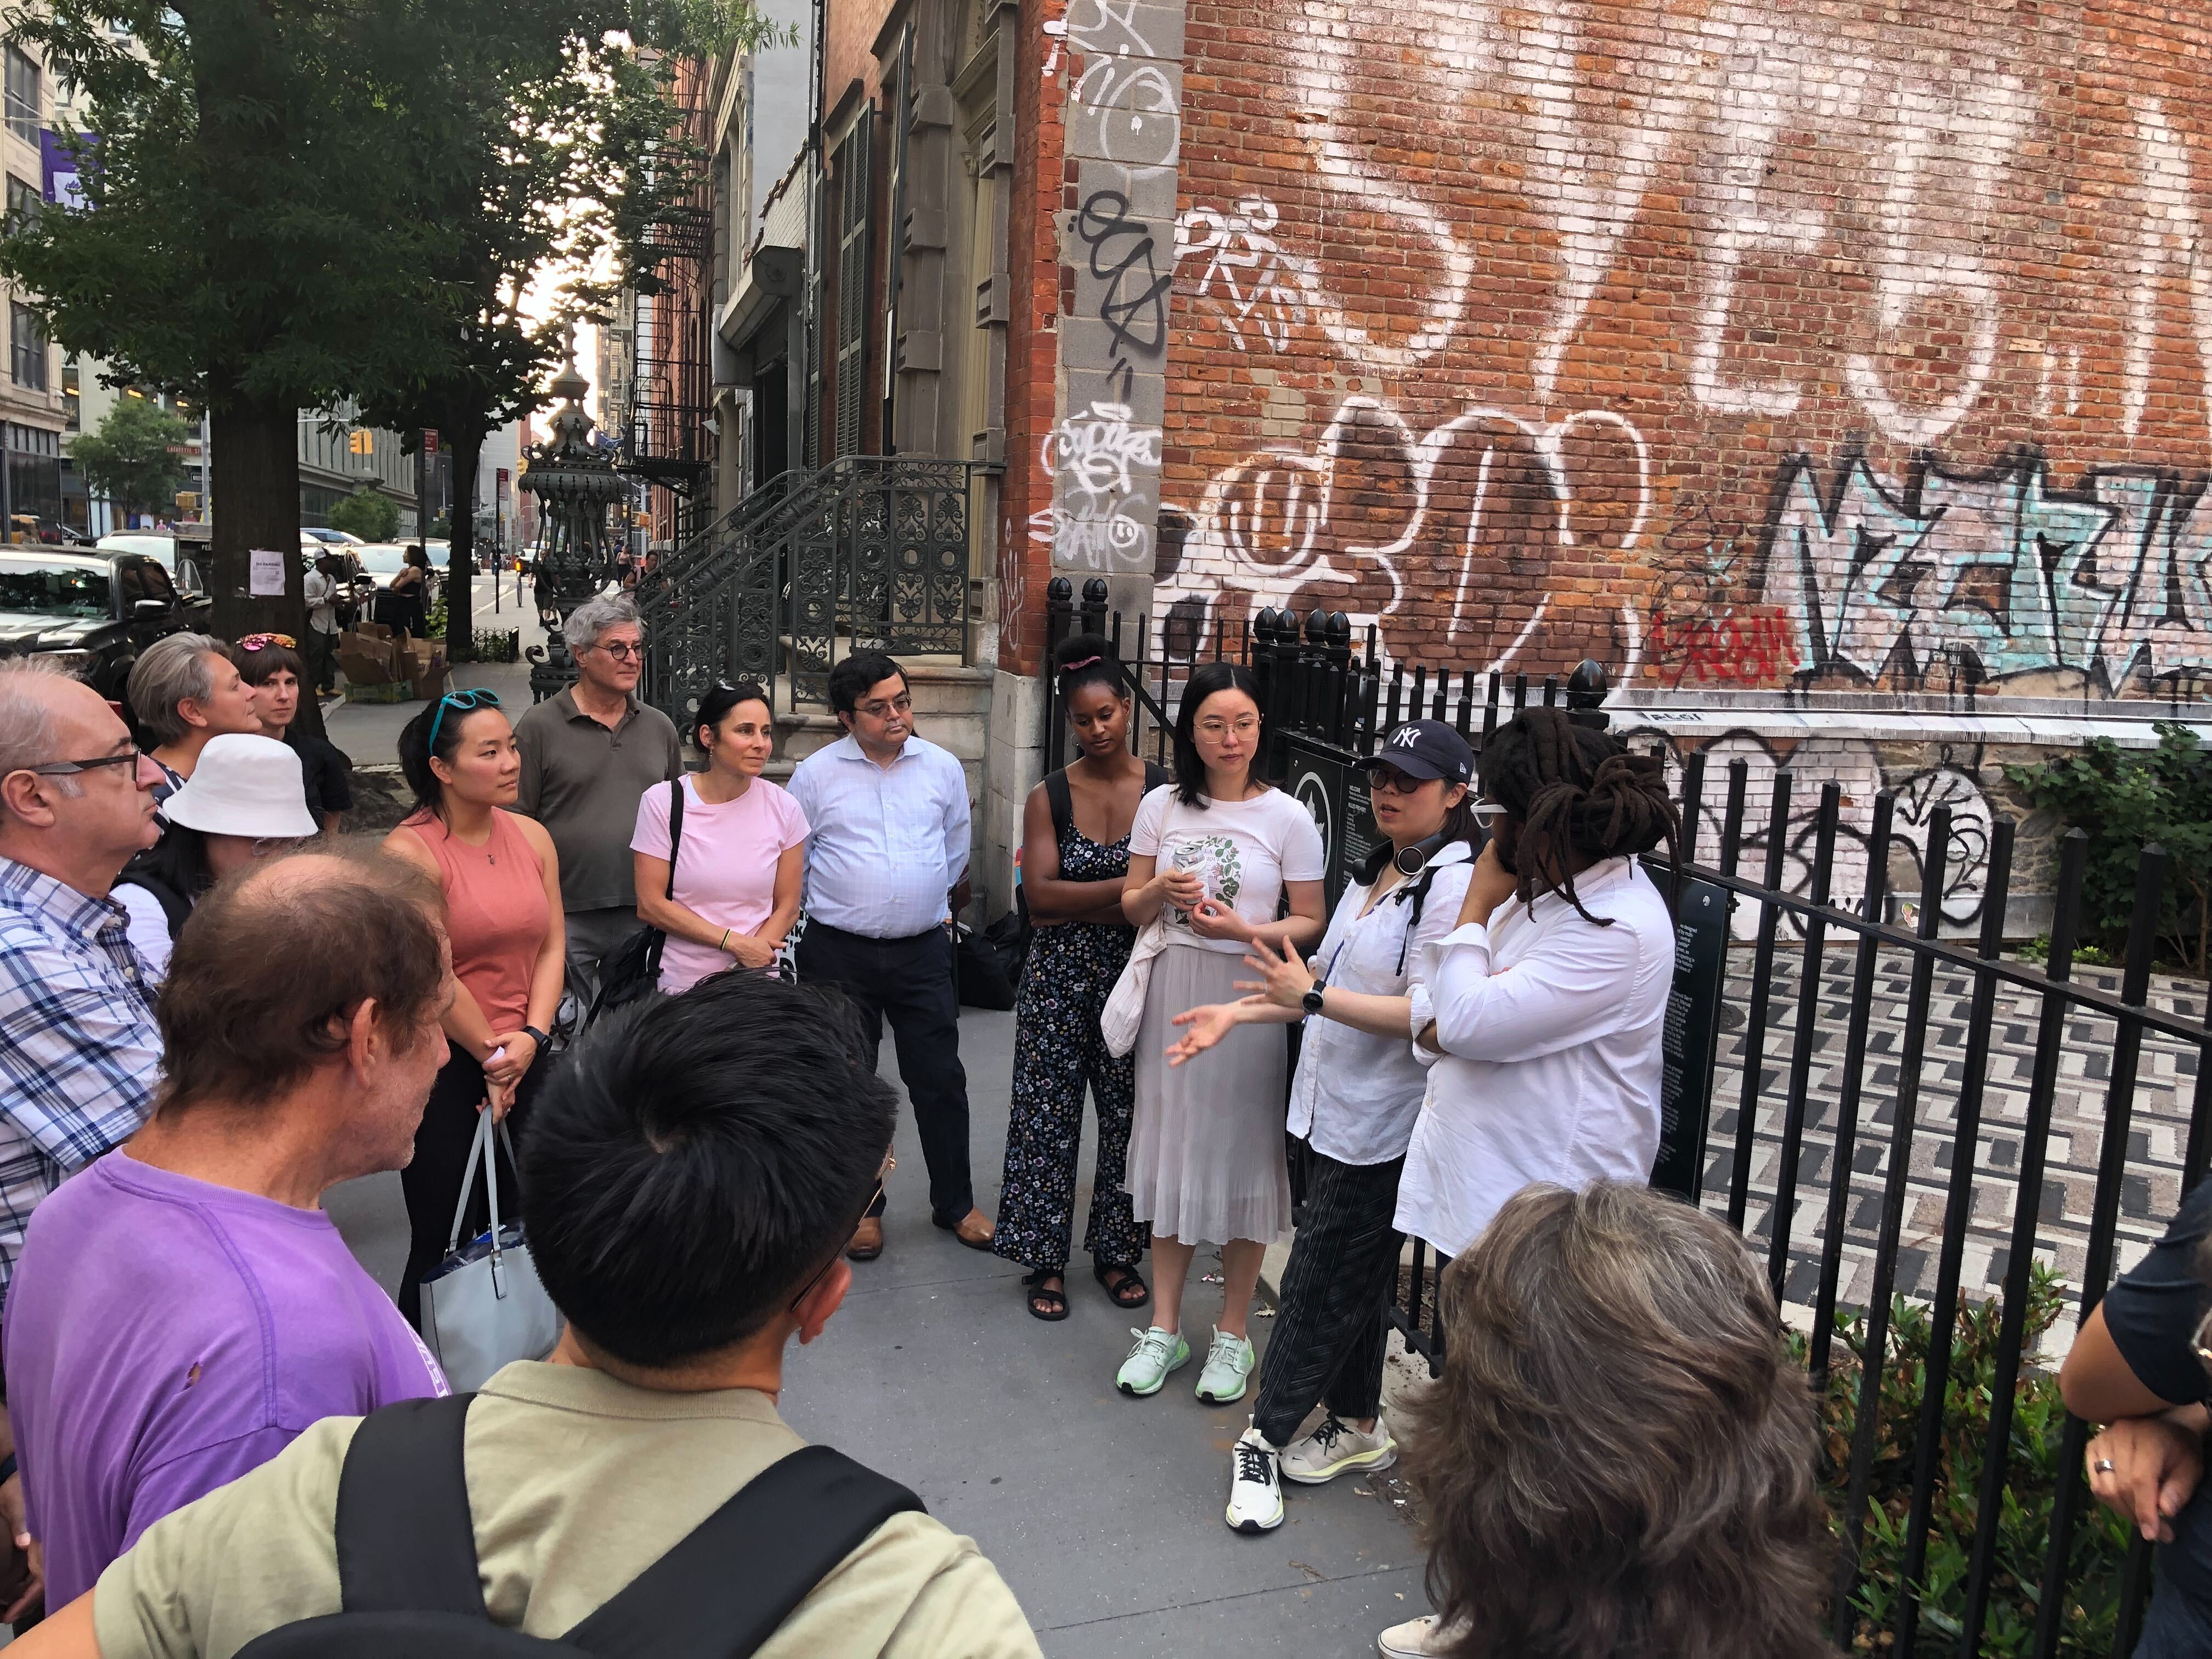
AD&Co learning about the history of Manuel Plaza, a beautiful gathering spot dedicated to the impact of African Diaspora in the development of New York. -
 AD&Conversations Improving Mortgage Data: A Data Exchange for Mortgage EcosystemPodcast
Tune in to Eknath Belbase's interview with Michelle Stepien Breier & Richard Cooperstein as they discuss their latest Pipeline article “Improving Mortgage Data: A Data Exchange for the Mortgage Ecosystem.” The interview highlights key points from the article as they share their vision of a mortgage data exchange. If you’re intrigued and eager to learn more, hit play or click the link to read the full article!
Login is required to access this Pipeline article.
-
 Mortgage Weather Hazard Risk: A Three Body ProblemEvents
At the recent AmeriCatalyst ‘Going to Extremes’ Climate, Housing and Finance Leadership Summit, I presented a session on how risks related to weather-related losses impact the housing finance system.
Until recently, weather-related losses were almost fully segmented from the risks borne by investors in mortgages and mortgage-backed securities. Most mortgages require that borrowers retain property insurance, so mortgage investors for the most part assumed that insurance or government assistance would cover property damage and protect the value of the mortgage collateral.
A few large weather events such as hurricanes Katrina, Irma and Sandy as well as wildfires in California led the mortgage market to recognize that delinquency immediately following a major weather event may not be indicative of a borrower’s ability to make mortgage payments over longer time horizons. Thus, the mortgage market introduced more flexible forbearance for weather-related delinquencies. Still, mortgage investors assumed, for the most part, that homes would be insured and weather-related losses would be small and easily diversified.
The recent spate of insurance firms exiting property insurance markets in Florida and California and rapid increases in premiums for borrowers who can purchase insurance has raised the specter that mortgages may be exposed to weather-related losses and that fewer homes may be eligible for mortgage financing.
While the structure of the housing finance system is quite complex, the issues associated with weather-related losses can be understood by focusing on three main players.
- The Borrower
- The Lender
- The Property Insurer
The Borrower seeks leverage and stable cost of housing and is willing to take on long-term risk of changes in the value of the home and maintenance cost. Borrowers often do not have the resources to cover significant damage to their homes or sustained loss of employment income. Risk management is to default on the loan if they do not have sufficient income and the home value declines below the amount of the loan
The Property Insurer is willing to take on diversified hazard risks in exchange for an actuarially sound premium. When there are losses, the borrower/homeowner files a claim and is reimbursed for the costs to restore the home. Insurance is provided on an annual basis, and the insurer has no obligation to keep prices the same or renew insurance. Risk management for the insurer is annual repricing or withdrawal from a market if regulators do not allow them to charge the premiums they request.
The Lender is seeking investments that exceed their cost of funds. The mortgage market is willing to provide funding and take on interest rate/prepayment risk. The market has various mechanisms to cover and distribute credit risk, many of which involve segmenting the various risks to investors with specific investment objectives. Risk management for non-payment by the borrower in the mortgage market is foreclosure. Thus, the mortgage market cannot provide stable homeownership for weather-related losses and generally, mortgage investors are not interested in taking on property hazard risks. As a result, the mortgage market uses “forced place insurance” when a borrower’s property insurance lapses or is not renewed.
There are roughly $13 trillion of mortgages outstanding in the US. These generate approximately $900 billion of annual payments of principal and interest. Of that amount, approximately $60 billion, or about 50 basis points per year, goes to the providers of credit guarantees like FHA, Fannie Mae and Freddie Mac and private insurance. Coincidently, the amount of homeowners’ insurance premiums is in the same ballpark as the guarantee fees, with the median issuance premium around 40 basis points on the replacement value of the structure. The value of the loan and the value of the structure both represent somewhere around 50% to 70% of the total value of the property.
Both insurance and mortgages provide stability for home ownership and allow borrowers to shed risks that would otherwise make homeownership unstable and unaffordable.
While both mortgage guarantee fees and property insurance are designed to cover losses, the mechanism for addressing losses is very different. Insurance provides money to the homeowner to continue living in the house, while guarantee fees are used to cover losses associated with foreclosure, that is, removing the owner from the house.
Mortgages serve to provide borrowers with long-term stability in the cost of homeownership. Property insurance, on the other hand, does not provide long-term stability as insurance is repriced annually and firms that are unable to operate profitably due to inability to adjust premiums to current levels of loss exit the market.
The change in the costs of property insurance due to more frequent weather events has upset the functioning of the housing finance system. Increased insurance costs and the potential for unavailable insurance have the potential to shift the risk of weather events to the mortgage market and the mortgage credit guarantees. However, the mechanism of the mortgage market to address losses, that is, foreclosure, is not suited to the problem of properties needing repairs to be livable.
Even if insurance is available, rapid increases in the cost of insurance may cause borrowers to default on loans when they can no longer afford the mortgage payments and the increased insurance costs. Additionally, higher insurance costs may decrease the value of homes, increasing the frequency and severity of loss.
Moreover, insurance that merely covers losses may be a disservice to the borrower and their communities. Houses that are restored, possibly to updated building codes, may still be subject to future losses and unaffordable insurance. Money spent on higher insurance premiums is money not spent on making properties and communities more resilient.
As mentioned earlier, one bright spot has been that the mortgage market has recognized that forbearance is a better solution for borrowers who are delinquent on their loans due to weather-related disruptions. And that often by waiting for the borrower to receive insurance payments or otherwise find financing for repairs, foreclosure and the associated losses can be avoided.
While the mortgage market can accommodate some degree of loss from weather events, we believe that it would be better to recognize the need to restructure the delivery of property insurance and find a solution that provides longer-term certainty for property insurance to the borrower and avoid the use of foreclosure as a method of addressing weather-related loss.
The S-Curve Archives
-
News
As housing faces more climate threats that result in more losses, the insurance program that it sits on is teetering on the brink of collapse. Yet, the home insurance market has three distinct stakeholders that have competing priorities, and today, there is no motivation for a collaborative solution.
Understanding how to strengthen and protect the current structure requires looking at the cost burdens along with the risk for each of those parties.
-
 Thoughts
There has been a flurry of activity in the mortgage markets since the 2018 passage of the Economic Growth, Regulatory Relief, and Consumer Protection Act. This act requires the Federal Housing Finance Agency (FHFA, now known as US Federal Housing) to validate and modernize the credit score models used in the housing finance system. It should be noted that so far, the discourse has been around mortgages sold to the Enterprises (Fannie Mae and Freddie Mac). Ginnie Mae has not provided any guidance on their plans to start using new credit score models.
-
 Events
Andrew Davidson & Co., Inc (AD&Co) proudly sponsored IMN’s 11th Annual Mortgage Servicing Rights (MSR) Forum by Informa at the New York Hilton Midtown. Senior modeler Daniel Swanson joined the “Managing Delinquencies & Forbearance Value” panel in discussing how servicers are adapting to today’s market and the evolving delinquency trends.
-
 Podcast
Tune in to our fourth episode of AD&Conversations with Kevin Lin and Eknath Belbase, our product lead for our Climate model. In this episode, they discuss the new Climate Impact Suite (CIS) pilot project, and Belbase outlines several challenges the team is navigating, including:
-
Podcast
Tune in to our fourth episode of AD&Conversations with Kevin Lin and Eknath Belbase, our product lead for our Climate model. In this episode, they discuss the new Climate Impact Suite (CIS) pilot project, and Belbase outlines several challenges the team is navigating, including:
-
Podcast
Andrew Davidson was invited to speak on Equifax's Market Pulse Podcast titled, "Driving Efficiency and Resilience in the Mortgage Industry" live at the 2025 MBA Annual Convention in Las Vegas.
Andy explains how variations in data files can distort risk assessment, creating a dual risk for lenders: extending credit to borrowers more likely to default while overcharging customers whose risk is overstated.
-
 Thoughts
Our latest Policy Perspective written by Richard Cooperstein offers an analysis of the U.S. housing and mortgage finance markets, focusing on key trends and forward-looking risks. While housing markets are not fully efficient, they do respond to economic imbalances which create opportunities and vulnerabilities. This article explores how demographic shifts, credit access, interest rates, and climate risks shape both housing demand and supply.
Key findings include:
-
Podcast
Join Kevin Lin in a conversation with Richard Cooperstein as they dive into Kinetics, AD&Co's modular platform designed to deliver the full power of our models and analytics; with the flexibility to license only the tools you need.
-
Thoughts
The latest Policy Perspectives paper “Competing Claims in Privatization of Fannie Mae and Freddie Mac” is now available!
Nearly 20 years ago, on September 6, 2008, the GSEs, Fannie Mae and Freddie Mac entered conservatorship. Since that time there have been many proposals to restructure, eliminate or release the GSEs. Once again there is talk about the privatization of Fannie Mae and Freddie Mac.
-
 Thoughts
AD&Co held our annual employee meeting in Detroit, Michigan. In addition to gathering everyone in person to socialize and strategize, we use these annual meetings to learn about different cities, especially with regard to housing market dynamics.
We chose Detroit because the oft-maligned city is undergoing a significant renaissance, and we wanted to explore the area and learn how housing may have played a role in both Detroit’s decline and rebirth.