
Welcome to The S-Curve
Now you will be able to receive the latest announcements, product updates, and our insights on the mortgage market in real time.
The name of the blog, the S-Curve, is a reflection of our logo and the central feature of our prepayment model. S-curves are seen in nature in many phenomenon, from population growth to prepayment and default models. Our first S-curve, in the early 1990s, used the arctangent function, then piece-wise linear functions, and evolved over time to be more complex and vary by FICO, loan size and LTV. This evolution encapsulates both the timeless nature of fundamental relationships and constant innovation to describe them better over time.
We hope you find the information useful and we look forward to your feedback.
-
 Mortgage Weather Hazard Risk: A Three Body ProblemEvents
At the recent AmeriCatalyst ‘Going to Extremes’ Climate, Housing and Finance Leadership Summit, I presented a session on how risks related to weather-related losses impact the housing finance system.
Until recently, weather-related losses were almost fully segmented from the risks borne by investors in mortgages and mortgage-backed securities. Most mortgages require that borrowers retain property insurance, so mortgage investors for the most part assumed that insurance or government assistance would cover property damage and protect the value of the mortgage collateral.
A few large weather events such as hurricanes Katrina, Irma and Sandy as well as wildfires in California led the mortgage market to recognize that delinquency immediately following a major weather event may not be indicative of a borrower’s ability to make mortgage payments over longer time horizons. Thus, the mortgage market introduced more flexible forbearance for weather-related delinquencies. Still, mortgage investors assumed, for the most part, that homes would be insured and weather-related losses would be small and easily diversified.
The recent spate of insurance firms exiting property insurance markets in Florida and California and rapid increases in premiums for borrowers who can purchase insurance has raised the specter that mortgages may be exposed to weather-related losses and that fewer homes may be eligible for mortgage financing.
While the structure of the housing finance system is quite complex, the issues associated with weather-related losses can be understood by focusing on three main players.
- The Borrower
- The Lender
- The Property Insurer
The Borrower seeks leverage and stable cost of housing and is willing to take on long-term risk of changes in the value of the home and maintenance cost. Borrowers often do not have the resources to cover significant damage to their homes or sustained loss of employment income. Risk management is to default on the loan if they do not have sufficient income and the home value declines below the amount of the loan
The Property Insurer is willing to take on diversified hazard risks in exchange for an actuarially sound premium. When there are losses, the borrower/homeowner files a claim and is reimbursed for the costs to restore the home. Insurance is provided on an annual basis, and the insurer has no obligation to keep prices the same or renew insurance. Risk management for the insurer is annual repricing or withdrawal from a market if regulators do not allow them to charge the premiums they request.
The Lender is seeking investments that exceed their cost of funds. The mortgage market is willing to provide funding and take on interest rate/prepayment risk. The market has various mechanisms to cover and distribute credit risk, many of which involve segmenting the various risks to investors with specific investment objectives. Risk management for non-payment by the borrower in the mortgage market is foreclosure. Thus, the mortgage market cannot provide stable homeownership for weather-related losses and generally, mortgage investors are not interested in taking on property hazard risks. As a result, the mortgage market uses “forced place insurance” when a borrower’s property insurance lapses or is not renewed.
There are roughly $13 trillion of mortgages outstanding in the US. These generate approximately $900 billion of annual payments of principal and interest. Of that amount, approximately $60 billion, or about 50 basis points per year, goes to the providers of credit guarantees like FHA, Fannie Mae and Freddie Mac and private insurance. Coincidently, the amount of homeowners’ insurance premiums is in the same ballpark as the guarantee fees, with the median issuance premium around 40 basis points on the replacement value of the structure. The value of the loan and the value of the structure both represent somewhere around 50% to 70% of the total value of the property.
Both insurance and mortgages provide stability for home ownership and allow borrowers to shed risks that would otherwise make homeownership unstable and unaffordable.
While both mortgage guarantee fees and property insurance are designed to cover losses, the mechanism for addressing losses is very different. Insurance provides money to the homeowner to continue living in the house, while guarantee fees are used to cover losses associated with foreclosure, that is, removing the owner from the house.
Mortgages serve to provide borrowers with long-term stability in the cost of homeownership. Property insurance, on the other hand, does not provide long-term stability as insurance is repriced annually and firms that are unable to operate profitably due to inability to adjust premiums to current levels of loss exit the market.
The change in the costs of property insurance due to more frequent weather events has upset the functioning of the housing finance system. Increased insurance costs and the potential for unavailable insurance have the potential to shift the risk of weather events to the mortgage market and the mortgage credit guarantees. However, the mechanism of the mortgage market to address losses, that is, foreclosure, is not suited to the problem of properties needing repairs to be livable.
Even if insurance is available, rapid increases in the cost of insurance may cause borrowers to default on loans when they can no longer afford the mortgage payments and the increased insurance costs. Additionally, higher insurance costs may decrease the value of homes, increasing the frequency and severity of loss.
Moreover, insurance that merely covers losses may be a disservice to the borrower and their communities. Houses that are restored, possibly to updated building codes, may still be subject to future losses and unaffordable insurance. Money spent on higher insurance premiums is money not spent on making properties and communities more resilient.
As mentioned earlier, one bright spot has been that the mortgage market has recognized that forbearance is a better solution for borrowers who are delinquent on their loans due to weather-related disruptions. And that often by waiting for the borrower to receive insurance payments or otherwise find financing for repairs, foreclosure and the associated losses can be avoided.
While the mortgage market can accommodate some degree of loss from weather events, we believe that it would be better to recognize the need to restructure the delivery of property insurance and find a solution that provides longer-term certainty for property insurance to the borrower and avoid the use of foreclosure as a method of addressing weather-related loss.
-
 Agency LDM+ Available in Milliman M-PIRe™Products
Andrew Davidson & Co., Inc (AD&Co) is thrilled to announce an expanding relationship with a Third-Party Vendor! AD&Co enjoys working with countless analytical providers to offer our clients seamless solutions and we would like to welcome Milliman M-PIRe™ to the team!
Milliman’s Integrate Solutions have supported AD&Co’s LoanDynamics Model (LDM) for many years. We've expanded on that relationship to include Milliman M-PIRe™ software. Milliman M-PIRe™ now supports AD&Co’s Agency+ LoanDynamics Model (Agency LDM+) to offer clients an industry-leading solution. AD&Co’s Agency LDM+ forecasts prepayments, delinquencies, defaults and loss probabilities, which are fed into Milliman M-PIRe™, a valuation and securitization software that produces advanced analytics of structured mortgage credit risk (CRT).
Today’s financial markets have taught us the importance of evaluating and managing financial risks. Milliman’s integration of AD&Co’s Agency LDM+ into the M-PIRe™ solution allows reinsurers and mortgage insurers to analyze CRT transactions using a multi-model framework when implementing risk and portfolio management strategies.
AD&Co would like to thank Milliman for their unparalleled support of our Agency LDM+ in the M-PIRe™ software. We truly appreciate their dedication to servicing mutual clients to ensure their success.
Interested in learning more about joint Milliman M-PIRe™ and Agency LDM+ solution? Please contact Jonathan Glowacki at jonathan.glowacki@milliman.com.
-
 Federal Home Loan Bank of San Francisco's Innovations in Mortgage Finance SymposiumEvents
The Federal Home Loan Bank of San Francisco directed the Urban Institute to develop innovative and actionable ideas to close the gap between white and black homeownership rates, which is as wide today as before the Fair Housing Act, enacted 60 years ago. Homeownership is crucial to a fairer society because working and middle-class families most commonly create inter-generational wealth by owning homes with amortizing mortgages. Urban Institute’s eighteen-month effort culminated in a symposium in February in Los Angeles attended by dozens of housing experts. The Borrowers Mutual Escrow Fund (BMEF), which I developed a few years ago, was included in the Urban Institute study, and I was invited to discuss it at the symposium.
A few key themes emerged from the symposium. One centers around replacing decades-old credit scores with modern metrics that better reflect borrower financial condition as the consumer financial footprint has become increasingly digitized, especially among minority populations. These metrics generally extend beyond traditional credit profiles to include other important measures of borrower financial condition such as digitized cash flow data, telecom/utility data and others. A fair amount of evidence already shows that modernized metrics assess homeownership readiness much better than old ones. Reducing uncertainty reduces cost.
Another theme that includes the BMEF, is that when trying to expand homeownership, liquidity and cash flow stability can be more critical to the success of marginal borrowers than traditional credit scores and down payments. Conscientious borrowers generally strive to restart paying their mortgages after short delinquencies if given the chance. Empirical support for this view includes delinquency performance through repeated climate events (e.g., hurricanes and floods) and the success of generalized forbearance during the COVID-19 pandemic.
This has turned decades of loss mitigation wisdom on its head. The Massachusetts state mortgage insurance program has included unemployment benefits for almost 20 years to resounding success. This program provides borrowers with fragile liquidity and volatile income, with a few months of payment reserves between jobs (e.g., consistently succeeds in preventing delinquency even through the financial crisis of 2007 and the COVID-19 pandemic). The GSEs and FHA have now made forbearance their initial loss mitigation response to borrower delinquency.
The BMEF proposes that borrowers put 3% of their house value into an administered escrow account instead of towards a down payment. It’s well-known that reserves are crucial to borrower success and placing reserves into escrow to be used for income interruption or unexpected maintenance will make reserves even more effective. Money in such accounts will always reduce risk compared with small down payments for borrowers, servicers, mortgage insurers and guarantors. This is provably true because the escrow funds are very liquid for payments, while the liquidity value of small down payments is effectively zero. Further evidence is that reperformance rates for delinquent borrowers are higher for borrowers with lower credit scores than for those with higher credit scores.
Borrowers pay mortgage insurance and guarantee fees to compensate insurers for risk, but it does not impact borrower ability to pay. By contrast, putting aside borrower funds for financial stress reduces risk throughout the value chain. Since it is borrower money in the first place, no subsidy is needed, but risk declines because liquidity is improved. Finally, borrower escrows managed by servicers for taxes and insurance are individual. However, BMEF escrows can be combined across borrowers to generate large diversification gains. Even among traditionally risky borrowers, perhaps 75% of them will never become delinquent, so it’s likely that the benefit limit can exceed the average contribution.
-
 Mortgage Data Exchange Presentation at #HousingDC23Events
The Data Foundation of Mortgage Finance
Homeownership is the largest source of wealth accumulation and inter-generational wealth transfer for the working and middle class. However, the non-interest cost of financing is always an obstacle for first-time and low-wealth buyers, and underserved populations.
- How much of the up-front and the ongoing cost of mortgages arise from the cost of data?
- What is a Mortgage Data Exchange, and how does it make the mortgage data market more efficient and reduce the cost of originating, servicing, investing, studying, and regulating mortgage finance?
Join me as I speak on these at the virtual #HousingDC23 on Wednesday, September 27th at 3:30 PM ET on a panel titled “Expanding Access and Transparency Through Alternative Data.”
Click here to watch the session on demand now!
-
 Mortgage Origination in a Post-COVID-19 WorldThoughts
In this blog post, we used the recently updated Mortgage Market Statistical Annual to examine the dynamics of residential loan origination by state and by market segments and highlight important trends.
From mid-2020 until April 2022, the Fed Funds rate was zero and fixed rate mortgage rates were historically low at about 3% (see Figure 1). Thereafter, the Fed began raising the Fed Funds rate to 5% today and fixed rate mortgage rates have doubled. Mortgage payments became unaffordable to many potential buyers and the mortgage origination volume dropped drastically across market segments and states by 80%. Predictably, the refinance market disappeared. Figure 2 shows that the origination volume for different mortgage products decreased drastically from Q1 2021 to 2023.
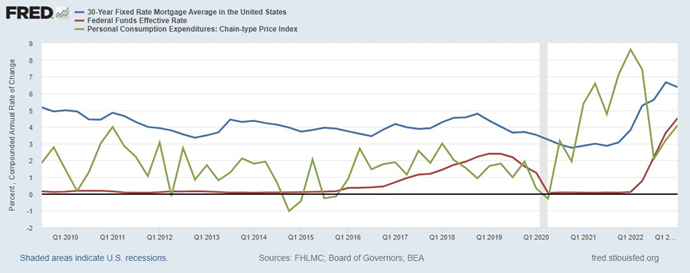
Figure 1. 30-Year Mortgage Rate, Fed Funds Effective Rate and PCE Price Index
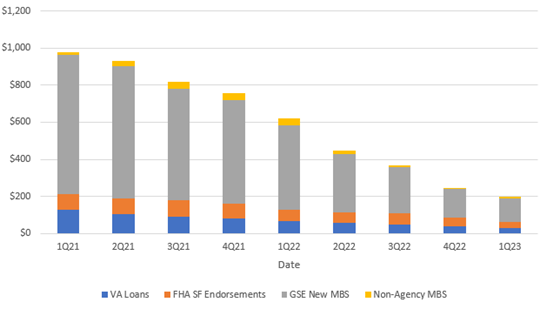
Figure 2. Origination Volume by Market Composition (Dollars in Billions)
Homeowners with low-rate mortgages have a strong financial incentive not to sell when facing the prospect of buying a new house with a mortgage rate twice as high (lock-in effect). These homeowners on the sidelines reduce both the supply and demand for housing. The countervailing impacts on price make the ultimate effect unclear; prices could rise or fall, but the changes are likely to moderate.
Figure 3 shows two things; (1) the housing price spike during the pandemic when rates were so low and the predicted recent collapse when rates rose and (2) turning points in housing prices lead to turning points in new construction rates weighted by population.
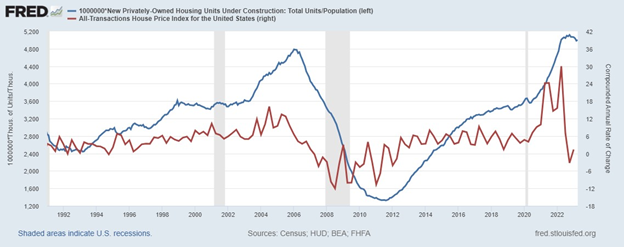
Figure 3. Housing Units Under Construction vs HPI
Looking at the States
Across the 50 states, plus Washington D.C. and Puerto Rico, origination dropped 48% from 2021 to 2022. For some background, YoY changes for the past few months have been positive, with 2019 to 2020 year-over-year (YoY) showing a 78% increase. We have to go back to 2016 to 2017 to see a negative 10% YoY drop and 2017 to 2018 a negative 9% drop. Among the most populous states, California suffered the largest drop YoY, declining by a whopping 60%. Some other states with a big YoY drop in origination include Maryland, 55%, Virginia, 54% and Massachusetts, 53%. On the other end, Texas and Florida had the smallest YoY losses at around 33%.
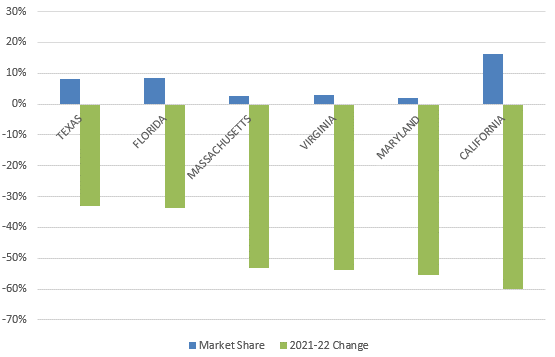
Figure 4 Originations by State
The situation in California, the most expensive state with the most expensive housing market was obvious; the escalating rate hikes priced many potential buyers out of the housing market in a state already hurt by the high income and property taxes.
The situations in Florida and Texas were drastically different. As low tax states, they represented good buying options even in a severe market turn and suffered the least drops.
Naturally, people are motivated to move to more tax-friendly states such as Florida when they retire. As the global pandemic hit and changed how people live and work, it further amplified that migration trend. Workers who once needed to live in states with hot employment markets like California’s tech hub can now work remotely and leave for other lower-cost states.
From Refinance to Purchase
The ten consecutive Fed rate hikes eliminated the refinance boom and deterred existing borrowers from moving, a combination leading to the plunge of origination. The refinance share has fallen from 71% in Q1 2021 to 16% in Q4 2022. On the turnover side, purchasing activities are still ongoing amidst the high rate environment. Purchase volume is not as drastically changed but still has fallen 13% from 2021. Figure 3 still shows a very steady volume of purchase originations over the past two years, despite its obvious decline over the past months. The decrease of the purchase volume can be attributed to the “lock in effect.”[1] The lock in effect is visible for discount mortgages as it deters potential sellers from giving up their current low-rate loan and finance next property with a more expensive one even if they have plans to relocate.
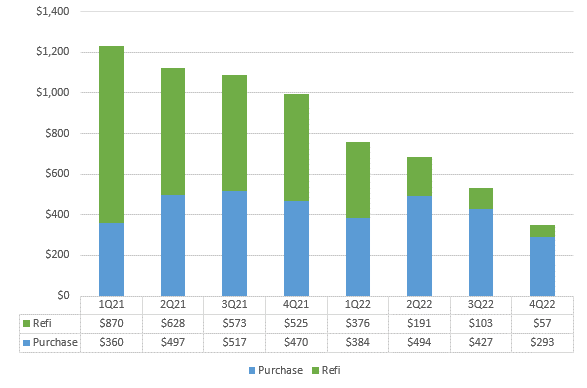
Figure 5. Purchase vs Refi Origination Volume (Dollars in Billions)
Looking Forward
We will continue to monitor changes in origination trends and their connection with affordability and home prices in our borrower behavior and home price modeling. For additional insight, read AD&Co’s HPI Outlook Update by Alex Levin.[2]
[1] Baker, Joni, and Daniel Swanson. “How to Use AD&Co’s Deep Discount and Super Premium S-Curve Tuning.” Quantitative Perspectives (May 2023).
[2] Levin, Alex. “AD&Co’S HPI Outlook Update: Flat, But Multidirectional.” The Pipeline, no. 182 (June 2023).
The S-Curve Archives
-
 Thoughts
Over the past summer, Andrew Davidson & Co., Inc. (AD&Co) was pleased to have Stephanie Duenas and Anika Chatterjee interning with us at our office in New York City. During this time, Stephanie and Anika performed a detailed analysis of mortgage performance data to consider the question of whether and how two credit scores, when available, could provide lift over a single score in predicting mortgage delinquencies.
-
 Events
AD&Co in Action: Volunteer & Cultural Days 2026
At Andrew Davidson & Co., Inc. (AD&Co), our values extend beyond the work we do for our clients. Humanity, inclusivity, dedication, citizenship, creativity, and integrity shape how we engage with one another and with our community. This August, members of the AD&Co team took the opportunity to put those values into practice during our Volunteer Day supporting Volunteers of America-Greater New York’s Operation Backpack® and our Cultural Day at Ellis Island.
-
 Thoughts
Recently, aggregators have crossed market borders by issuing residential mortgage-backed securities (RMBS) backed by owner-occupied (OO), GSE-eligible conforming loans. Additionally, conforming mortgage loans have drawn investment interest from insurance companies fronted by aggregators and evaluated by third-party firms. These developments constitute historically rare disintermediations of the nearly monopsonist purchases of conforming loans by the GSEs.
-
 Podcast
Join Rob Landauer in a conversation with Abe Martin as they discuss his recent Pipeline article, "Modeling the Balance Behavior of HELOC Borrowers." In this episode, they highlight key points from the article as he shares insights into the draw component of HELOCs and provide an update on the beta rele
-
News
We’re excited to announce a major addition to the Andrew Davidson & Co., Inc. (AD&Co) team. Industry leaders Kelli Sayres and Gene Park, known for building and scaling leading fixed-income analytics platforms, have joined AD&Co’s Business Development team.
-
 Thoughts
Building on our earlier research on expanded consumer attributes, AD&Co continues to explore how credit data contributes to modeling delinquency and prepayment risk, which are key drivers of mortgage servicing rights cash flows and valuation.
-
 Events
Andrew Davidson recently joined NFM Lending’s Greg Sher on the One On One podcast to discuss our recent white paper, “The Impact of Moving Away From the Tri-Merge Standard.”
-
 Events
AD&Co recently sponsored and attended SFVegas 2026 and Optimal Blue Summit 2026. This post shares the AD&Co team's unique perspectives and key takeaways from attending both conferences.
-
 News
AD&Co US Mortgage High Yield Indices
The Federal Reserve Economic Data (FRED) portal, housed by the Federal Reserve Bank of St. Louis, has been publishing AD&Co’s CRT indices since 2019. These series posted under the overall name of “US Mortgage High-Yield” include total return rates and credit and option-adjusted spreads (crOAS) – a projected return’s spread over Treasury (in the past, Libor). These series are available going back to 2014-end and tiered by CRT initial supports.
-
 Thoughts
In July 2025, the US Federal Housing Finance Agency (FHFA) announced that the government-sponsored entities (the Enterprises or GSEs), Fannie Mae and Freddie Mac, would permit lenders to choose between Classic FICO and VantageScore 4.0 credit score models for loans sold to the GSEs. FHFA also stated in a social media post that the tri-merge standard would be maintained for mortgage underwriting. Nevertheless, some mortgage industry stakeholders recommend moving away from the tri-merge standard for GSE mortgages in favor of a single or bi-merge report standard.