
Welcome to The S-Curve
Now you will be able to receive the latest announcements, product updates, and our insights on the mortgage market in real time.
The name of the blog, the S-Curve, is a reflection of our logo and the central feature of our prepayment model. S-curves are seen in nature in many phenomenon, from population growth to prepayment and default models. Our first S-curve, in the early 1990s, used the arctangent function, then piece-wise linear functions, and evolved over time to be more complex and vary by FICO, loan size and LTV. This evolution encapsulates both the timeless nature of fundamental relationships and constant innovation to describe them better over time.
We hope you find the information useful and we look forward to your feedback.
-
The Signal and The NoiseThoughts
Separating signal from noise is at the heart of what we do at AD&Co. One of the key tools we utilize for that purpose is a sophisticated set of model performance trigger reports. These monthly reports not only alert us to model drift but also point to possible causes for the drift.
In the mortgage market, changes in behavior on the part of both borrowers and lenders may create gaps between model projections and actual performance. Early analysis of these gaps provides rich information to our modelers based on which they can either identify temporary drifts in model performance or, more importantly, highlight fundamental changes in behavior that need to be captured in our models.
Every product type is monitored along the following four dimensions, with residuals defined as the monthly difference between projected and actual results:
Moving average: Are residuals deteriorating over time?
Trend: Are residuals consistently becoming more positive or negative?
Bias: Is the model persistently overpredicting or underpredicting actuals?
Magnitude: Are model misses large enough to matter?
Multiple types of triggers are useful for determining the seriousness of a breach as well as the type of adjustments that might be warranted in response. For example, a moving average warning might indicate a developing change in borrower behavior that may require either additional explanatory variables or more complex functions of existing variables to tighten the residuals. Alternatively, updated data may provide key information for refitting the model. A small but persistent bias, on the other hand, may be easily corrected with a simple tuning parameter adjustment.
These triggers also help us monitor performance at the factor level. Rather than simply observing, for example, how GNMA 15-year MBS are performing, we have triggers at different levels of credit score, LTV, note rate, and many other factors. This deep analysis, presented as an easy-to-use dashboard, quickly identifies possible causes of model drift.
In January, we will present a detailed review of our trigger methodology, and show how we use the reports to help set our modeling priorities in order to explain performance and, when necessary, modify our models to accommodate new behavioral patterns. For now, we will leave you with the following example of a segment of a trigger report for FHLMC MBS using LDM 2.2 with COVID tunings applied.
Happy Holidays!
Tom Parrent, Model Risk Management
October 2020 FHLMC Trigger Report
Trigger Type Bias Magnitude MovAvg Trend LoanType UPB FHLMC_30YR 2,085,272,108,356 ⬤ ⬤ ⬤ ⬤ Trigger Type Bias Magnitude MovAvg Trend LoanType Net Coupon UPB FHLMC_30YR 2.0 196,050,740,636 ⬤ ⬤ ⬤ ⬤ 2.5 253,743,515,938 ⬤ ⬤ ⬤ ⬤ 3.0 547,254,721,052 ⬤ ⬤ ⬤ ⬤ 3.5 498,363,756,722 ⬤ ⬤ ⬤ ⬤ 4.0 331,086,483,224 ⬤ ⬤ ⬤ ⬤ 4.5 152,994,012,086 ⬤ ⬤ ⬤ ⬤ 5.0 59,076,412,520 ⬤ ⬤ ⬤ ⬤ Legend Pass ⬤ Watch ⬤ Warning ⬤ -
Andrew Davidson & Co., Inc.’s LoanDynamics Models Empowers Fite Analytics’ MBS Analytics ServiceNews
Andrew Davidson & Co., Inc. (AD&Co), is proud to support Fite Analytics’ innovative cloud-native Mortgage-Backed Securities Analytics Service. The Fite Analytics solution incorporates AD&Co’s LoanDynamics models that provide forecasts of voluntary prepayments, defaults and losses that drive risk analytics across the mortgage-backed securities market with comprehensive coverage. To read the full press release click here.
-
Introducing the New AD&Co WebsiteNews
We are thrilled to announce that Andrew Davidson & Co., Inc. has launched a new look for ad-co.com. Some of the exciting new features of this site include:
-
A dynamic homepage highlighting the firm’s latest innovations, AD&Co client benefits, announcements, and Diversity, Equity and Inclusion efforts.
-
Our new blog titled The S-Curve that offers our latest announcements, product updates, and insights on the mortgage market in real time.
-
An enhanced solutions-focused structure organized by I Work In (includes industry and investment categories), Tools (product pages), Consulting, Insights (announcements and literature), and Client Portal (downloads portal and model resources).
-
About AD&Co includes Our Company and Diversity, Equity, and Inclusion sections which offer a look into the firm’s foundation, culture, and practices.
Please take the time to:
-
Register to access the new website. You will be prompted to set up a new password.
-
Kindly verify your contact information on your User Dashboard. If you need to update your information, please contact us.
Finally, we’ve updated our Terms of Use and Privacy Statement. You will be asked to accept them when you log in for the first time.
Please let us know feedback or concerns to ensure we continue to serve you well. Thank you.
-
The S-Curve Archives
-
 Thoughts
In July 2025, the US Federal Housing Finance Agency (FHFA) announced that the government-sponsored entities (the Enterprises or GSEs), Fannie Mae and Freddie Mac, would permit lenders to choose between Classic FICO and VantageScore 4.0 credit score models for loans sold to the GSEs. FHFA also stated in a social media post that the tri-merge standard would be maintained for mortgage underwriting. Nevertheless, some mortgage industry stakeholders recommend moving away from the tri-merge standard for GSE mortgages in favor of a single or bi-merge report standard.
-
News
As housing faces more climate threats that result in more losses, the insurance program that it sits on is teetering on the brink of collapse. Yet, the home insurance market has three distinct stakeholders that have competing priorities, and today, there is no motivation for a collaborative solution.
Understanding how to strengthen and protect the current structure requires looking at the cost burdens along with the risk for each of those parties.
-
 Thoughts
There has been a flurry of activity in the mortgage markets since the 2018 passage of the Economic Growth, Regulatory Relief, and Consumer Protection Act. This act requires the Federal Housing Finance Agency (FHFA, now known as US Federal Housing) to validate and modernize the credit score models used in the housing finance system. It should be noted that so far, the discourse has been around mortgages sold to the Enterprises (Fannie Mae and Freddie Mac). Ginnie Mae has not provided any guidance on their plans to start using new credit score models.
-
 Events
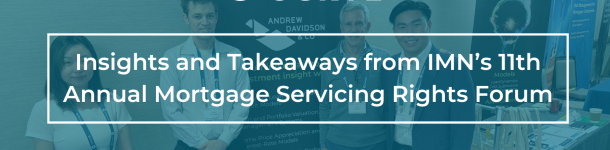
Andrew Davidson & Co., Inc (AD&Co) proudly sponsored IMN’s 11th Annual Mortgage Servicing Rights (MSR) Forum by Informa at the New York Hilton Midtown. Senior modeler Daniel Swanson joined the “Managing Delinquencies & Forbearance Value” panel in discussing how servicers are adapting to today’s market and the evolving delinquency trends.
-
 Podcast
Tune in to our fourth episode of AD&Conversations with Kevin Lin and Eknath Belbase, our product lead for our Climate model. In this episode, they discuss the new Climate Impact Suite (CIS) pilot project, and Belbase outlines several challenges the team is navigating, including:
-
Podcast
Tune in to our fourth episode of AD&Conversations with Kevin Lin and Eknath Belbase, our product lead for our Climate model. In this episode, they discuss the new Climate Impact Suite (CIS) pilot project, and Belbase outlines several challenges the team is navigating, including:
-
Podcast
Andrew Davidson was invited to speak on Equifax's Market Pulse Podcast titled, "Driving Efficiency and Resilience in the Mortgage Industry" live at the 2025 MBA Annual Convention in Las Vegas.
Andy explains how variations in data files can distort risk assessment, creating a dual risk for lenders: extending credit to borrowers more likely to default while overcharging customers whose risk is overstated.
-
 Thoughts
Our latest Policy Perspective written by Richard Cooperstein offers an analysis of the U.S. housing and mortgage finance markets, focusing on key trends and forward-looking risks. While housing markets are not fully efficient, they do respond to economic imbalances which create opportunities and vulnerabilities. This article explores how demographic shifts, credit access, interest rates, and climate risks shape both housing demand and supply.
Key findings include:
-
Podcast
Join Kevin Lin in a conversation with Richard Cooperstein as they dive into Kinetics, AD&Co's modular platform designed to deliver the full power of our models and analytics; with the flexibility to license only the tools you need.
-
Thoughts
The latest Policy Perspectives paper “Competing Claims in Privatization of Fannie Mae and Freddie Mac” is now available!
Nearly 20 years ago, on September 6, 2008, the GSEs, Fannie Mae and Freddie Mac entered conservatorship. Since that time there have been many proposals to restructure, eliminate or release the GSEs. Once again there is talk about the privatization of Fannie Mae and Freddie Mac.