
Welcome to The S-Curve
Now you will be able to receive the latest announcements, product updates, and our insights on the mortgage market in real time.
The name of the blog, the S-Curve, is a reflection of our logo and the central feature of our prepayment model. S-curves are seen in nature in many phenomenon, from population growth to prepayment and default models. Our first S-curve, in the early 1990s, used the arctangent function, then piece-wise linear functions, and evolved over time to be more complex and vary by FICO, loan size and LTV. This evolution encapsulates both the timeless nature of fundamental relationships and constant innovation to describe them better over time.
We hope you find the information useful and we look forward to your feedback.
-
 Policy Perspectives - Housing Market Dynamics and Mortgage RiskThoughts
Our latest Policy Perspective written by Richard Cooperstein offers an analysis of the U.S. housing and mortgage finance markets, focusing on key trends and forward-looking risks. While housing markets are not fully efficient, they do respond to economic imbalances which create opportunities and vulnerabilities. This article explores how demographic shifts, credit access, interest rates, and climate risks shape both housing demand and supply.
Key findings include:
- Weak demand fundamentals, especially among new homeowners
- Easing supply shortages and slowing price growth
- Elevated risk of broader housing price declines amid rising recession concerns
- Notable exposure of higher-coupon mortgages and servicing rights to interest rate and credit risks
Cooperstein also assess the resilience of mortgage-related assets under current and projected conditions.
Click here to read now!
-
 AD&Conversations: Exploring KineticsPodcast
Join Kevin Lin in a conversation with Richard Cooperstein as they dive into Kinetics, AD&Co's modular platform designed to deliver the full power of our models and analytics; with the flexibility to license only the tools you need. In this interview, they unpack insights from Eric Limjoco's recent Pipeline article, "Driving Sharper Insights with the Kinetics Reporting Engine," and share a sneak peek into what's coming with the Kinetics 2.0 release.
As a seasoned internal power user, Richard shares why this upgrade is an innovative enhancement for delivering comprehensive solutions across the mortgage space.
-
Policy Perspectives - Competing Claims In Privatization Of Fannie Mae And Freddie MacThoughts
The latest Policy Perspectives paper “Competing Claims in Privatization of Fannie Mae and Freddie Mac” is now available!
Nearly 20 years ago, on September 6, 2008, the GSEs, Fannie Mae and Freddie Mac entered conservatorship. Since that time there have been many proposals to restructure, eliminate or release the GSEs. Once again there is talk about the privatization of Fannie Mae and Freddie Mac.
Privatization faces many hurdles both political and financial. In his article, Andrew Davidson looks at some of the financial considerations and shows that any solution will require a compromise between competing financial claims.
Click here to read now! -
 Gritty Renaissance: AD&Co Visits DetroitThoughts
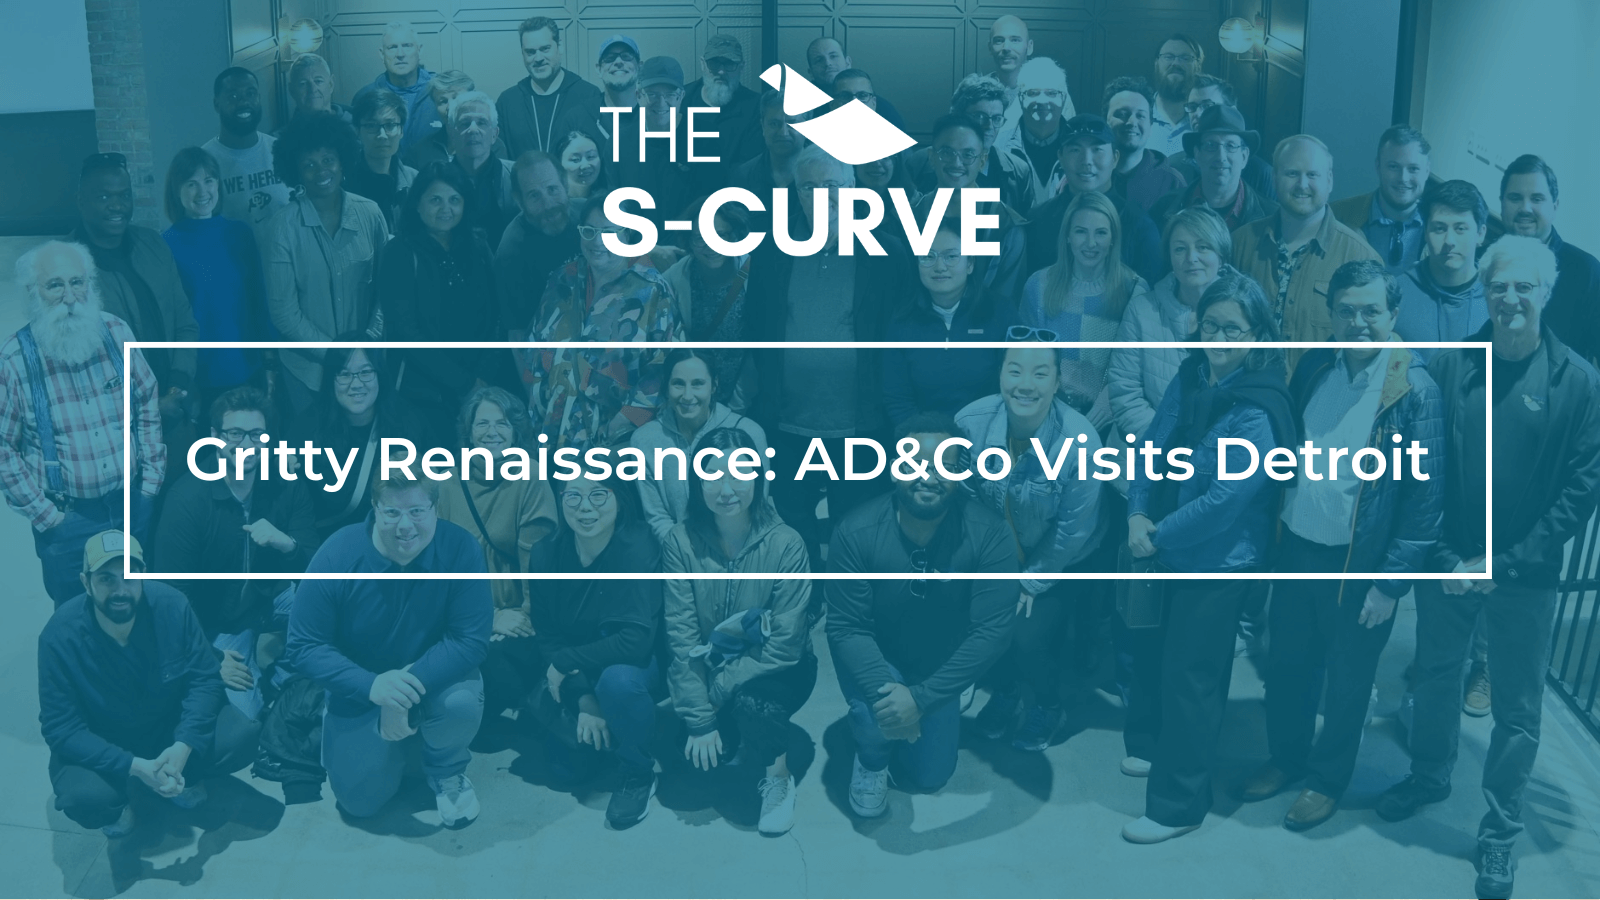
AD&Co held our annual employee meeting in Detroit, Michigan. In addition to gathering everyone in person to socialize and strategize, we use these annual meetings to learn about different cities, especially with regard to housing market dynamics.
We chose Detroit because the oft-maligned city is undergoing a significant renaissance, and we wanted to explore the area and learn how housing may have played a role in both Detroit’s decline and rebirth.
From the early 1900s through the mid-1960s, Detroit was an industrial and innovation powerhouse. Beyond automobiles, the southeastern Michigan area attracted new residents with jobs in everything from heavy industry to machine shops to transportation.
Detroit has always had a substantial share of single-family houses compared to other industrial hubs, which relied more on high-density multifamily housing. While homeownership rates were generally high, opportunities were not evenly dispersed, as racial redlining led to largely segregated neighborhoods and lower homeownership rates among blacks and ethnic minorities. Although redlining was common in the first half of the 20th century in many large American cities, Michigan set itself apart. Its Home Rule Act allowed a great deal of self-governance by small cities leading to the creation of dozens of very small towns, all with different public services and both subtle and overt discriminatory policies. The Home Rule Act also allowed large companies to heavily influence local taxation policy and effectively create low tax havens in small towns, thus starving the greater Detroit area of tax revenue.
Detroit started facing significant troubles in the late 1960s, as the 1967 race riots led to significant white flight. The OPEC embargo in the early 1970’s increased oil prices and opened the door to more fuel-efficient foreign competitors in auto manufacturing. The city’s decline began with significant population loss due to both unemployment and migration to suburban areas, resulting in deterioration of inner-city housing stock and severe underfunding of public services such as police, fire protection and education.
Long known for its grit and determination, Detroit started to come back in the 1990s and early 2000s as the auto industry recovered. However, much of that progress was lost during the Great Recession due to predatory lending and the second collapse of American automakers. Many large blocks of the inner city were left with only one or two houses standing, and arson for insurance money plagued the housing stock.
However, Detroit’s revival in the past ten years proved even bigger than all of its setbacks. The Lions, Tigers, Red Wings, and Pistons now all have their venues within easy walking distance of the revitalized downtown business and entertainment district. The city built a new riverfront parkway and renovated parks. Downtown has incredible energy once again, with bustling businesses and residential towers going up, not to mention the burgeoning art scene popping up in multiple locations.
Laura Grannemann, Executive Director, Rocket Community Fund & Gilbert Family Foundation, gave an overview of the organizations' endeavors in the community. As one of the nation’s largest mortgage lenders, their Detroit Home Repair Fund and Detroit Tax Relief Fund work to head off displacement through preventing tax foreclosure and eviction.
Detroit still faces many challenges, particularly in those neighborhoods hit hardest by out-migration, foreclosures, and underinvestment in city services. Wealth and influence remain highly concentrated, and the Home Rule Act micro towns remain an impediment to healthy Detroit finances and provision of basic services. Despite this, we found encouraging pockets of home-grown revitalization. Jeanette Pierce, president of City Institute, showed us how hyper-local organizing is bringing growth and renewal without troublesome gentrification and displacement. We met leaders from organizations such as the Southwest Detroit Business Association, Capital Impact Partners, and Live6 Alliance that advocate for fair housing and community engagement. Keeping people in the neighborhoods that multiple generations have called home is a hallmark of these local initiatives. Tactical rezoning has helped overcome some of the obstacles to development presented by Detroit’s traditional focus on detached single-family housing.
The team also met Ike Blessitt, who personifies Detroit’s gritty reputation. Ike grew up in Hamtramck, one of the Home Rule Act towns completely surrounded by Detroit. As a four-sport high school star athlete, Ike attracted the attention of Detroit Tigers scouts and eventually made it to the major leagues with the 1972 Tigers. Today, even as a 76-year-old double amputee, Ike has continued his 15 years of teaching individuals, aged 6 to 60, how to play baseball. Like the development efforts, Ike keeps it local to help inner-city kids by building a complete baseball training facility in his Detroit backyard. The Ike Blessitt Sports Academy attracts kids from throughout Detroit.
We came away from Detroit with a real appreciation for the daily challenges its residents overcome through innovation and community organizing. The lively sports and entertainment district will surprise new visitors, but digging deeper into the neighborhoods will show that this renaissance is just getting started.
-
 Introducing MARS+ as the Next Generation of Mortgage Analysis and Reporting SystemProducts
Andrew Davidson & Co., Inc (AD&Co) is pleased to announce the beta release of MARS+, the next generation of Mortgage Analysis & Reporting System (MARS), which has been in use since 2008 for performance reporting of AD&Co models. MARS+ aims to provide enhanced and advanced capabilities and features for mortgage analysis and reporting.
The new enhancements of MARS+ include:
- Simplified access to AD&Co models and data from a single page
- Enhanced filtering and stratification of back-testing data
- Distribution of data for key mortgage data analysis parameters
- Model performance visualization and tabular display for selected data of interest
- Customizable dashboards for effective reporting of actual and model results along with data characteristics
In what follows, we summarize how to use the various capabilities and features of MARS+.
Selecting, Filtering, and Stratifying Data of Interest
The initial screen of MARS+ labeled as ‘Model & Data’ provides user interface components that are grouped into three categories: (1) Model & Data Inputs, (2) Filters, and (3) Stratification.
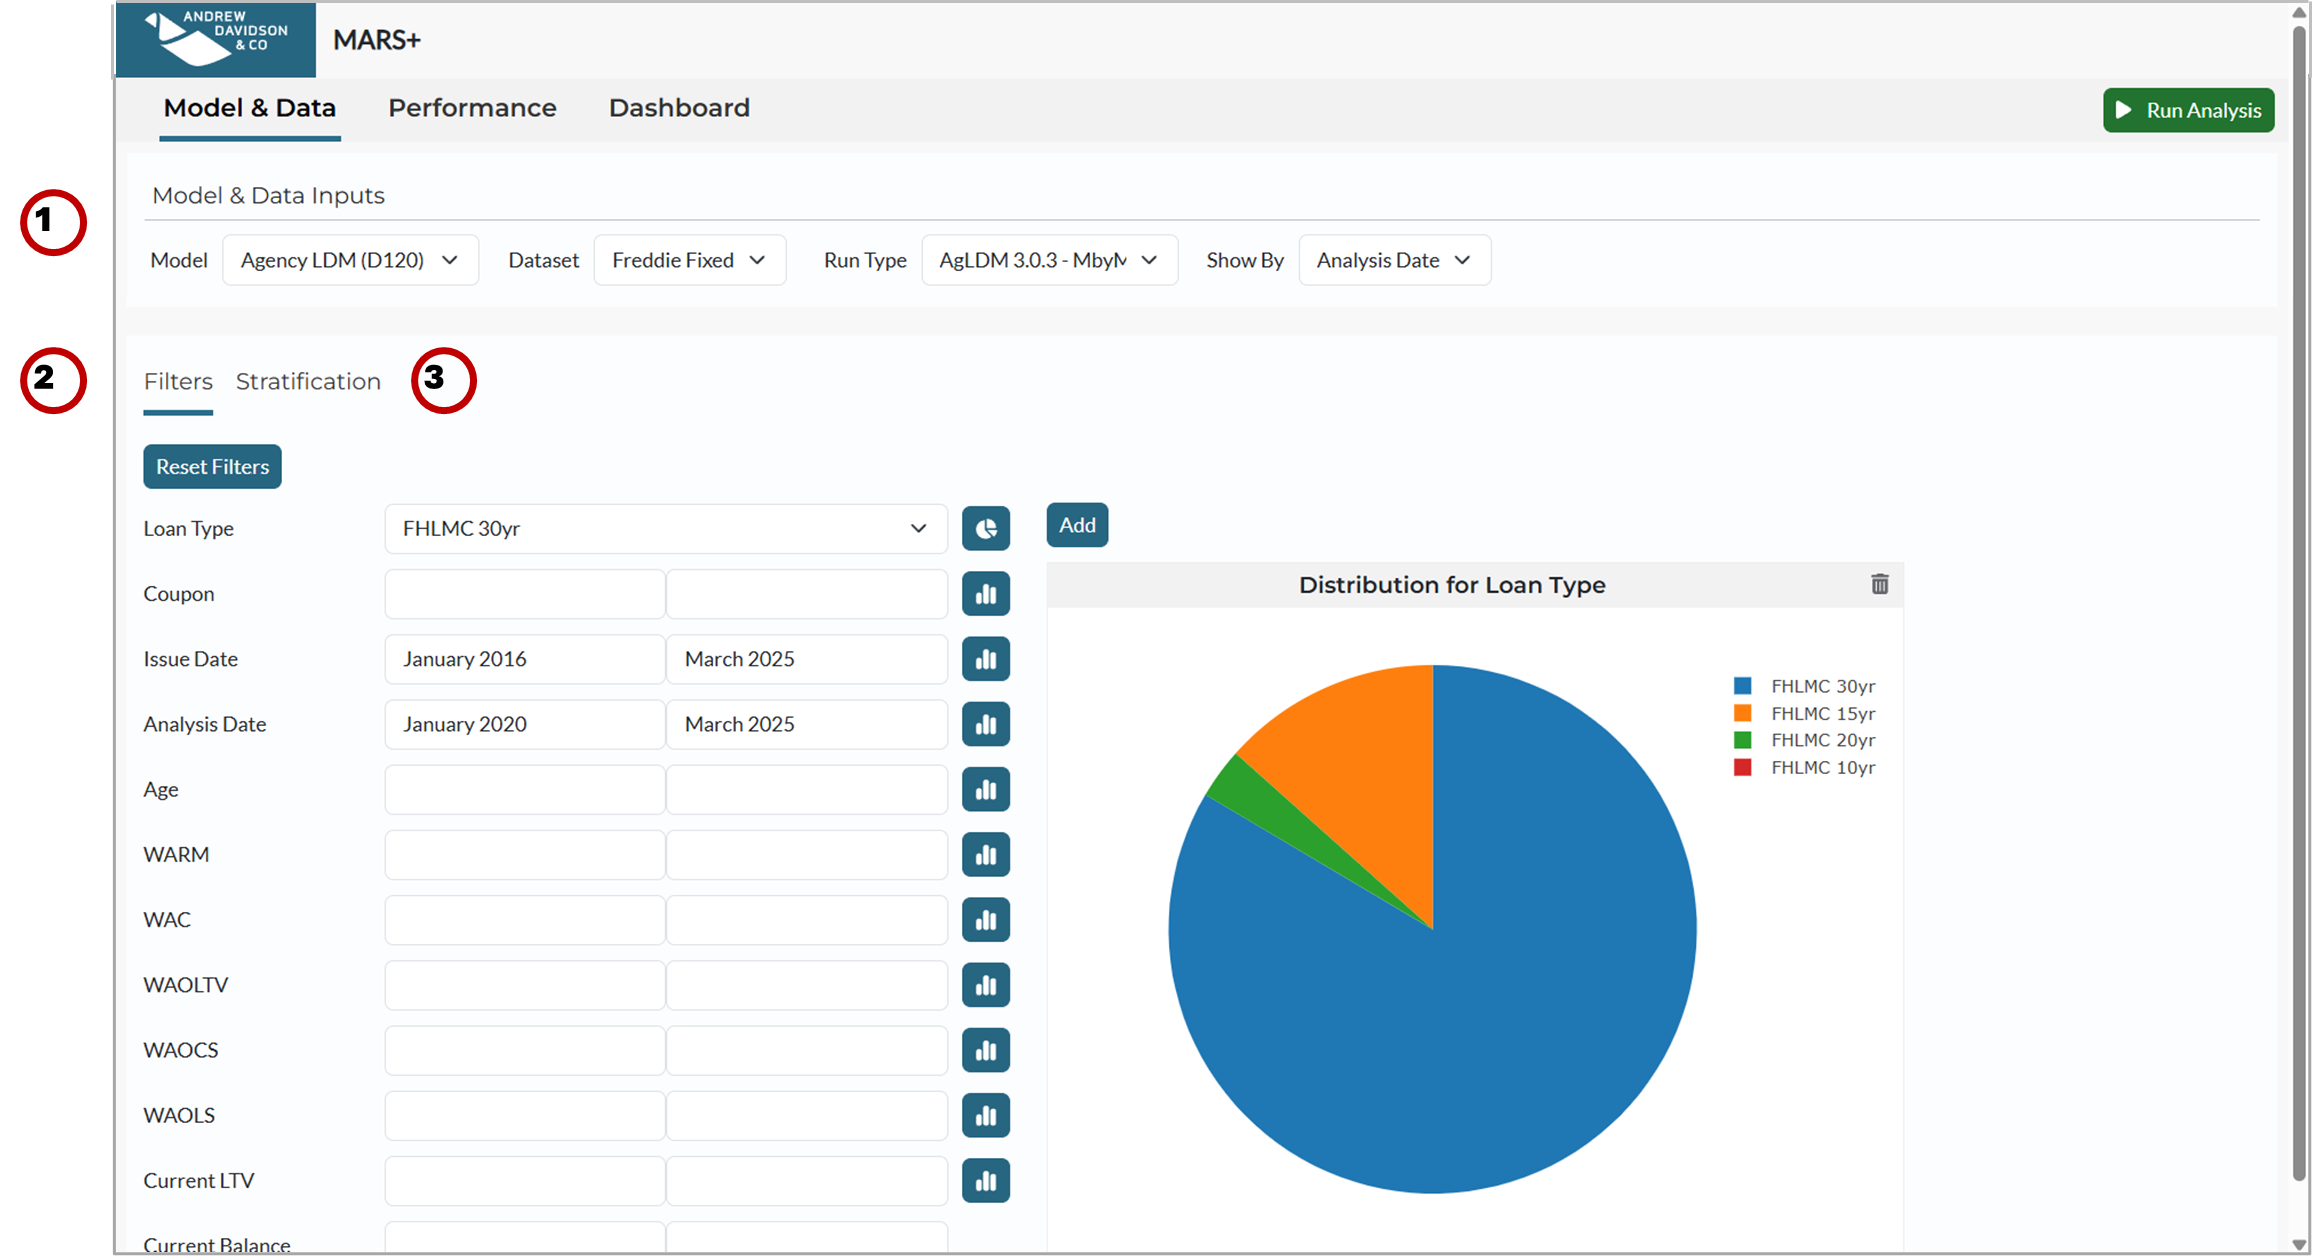
For selected filter and stratification data parameters, the ‘Model & Data’ panel also provides a distribution icon to the right of each filter and the parameter selected for stratification. Upon clicking on a distribution icon, the distribution of the selected data parameter is displayed as a pie chart or a bar chart to the right of filters or stratification bucket definitions.
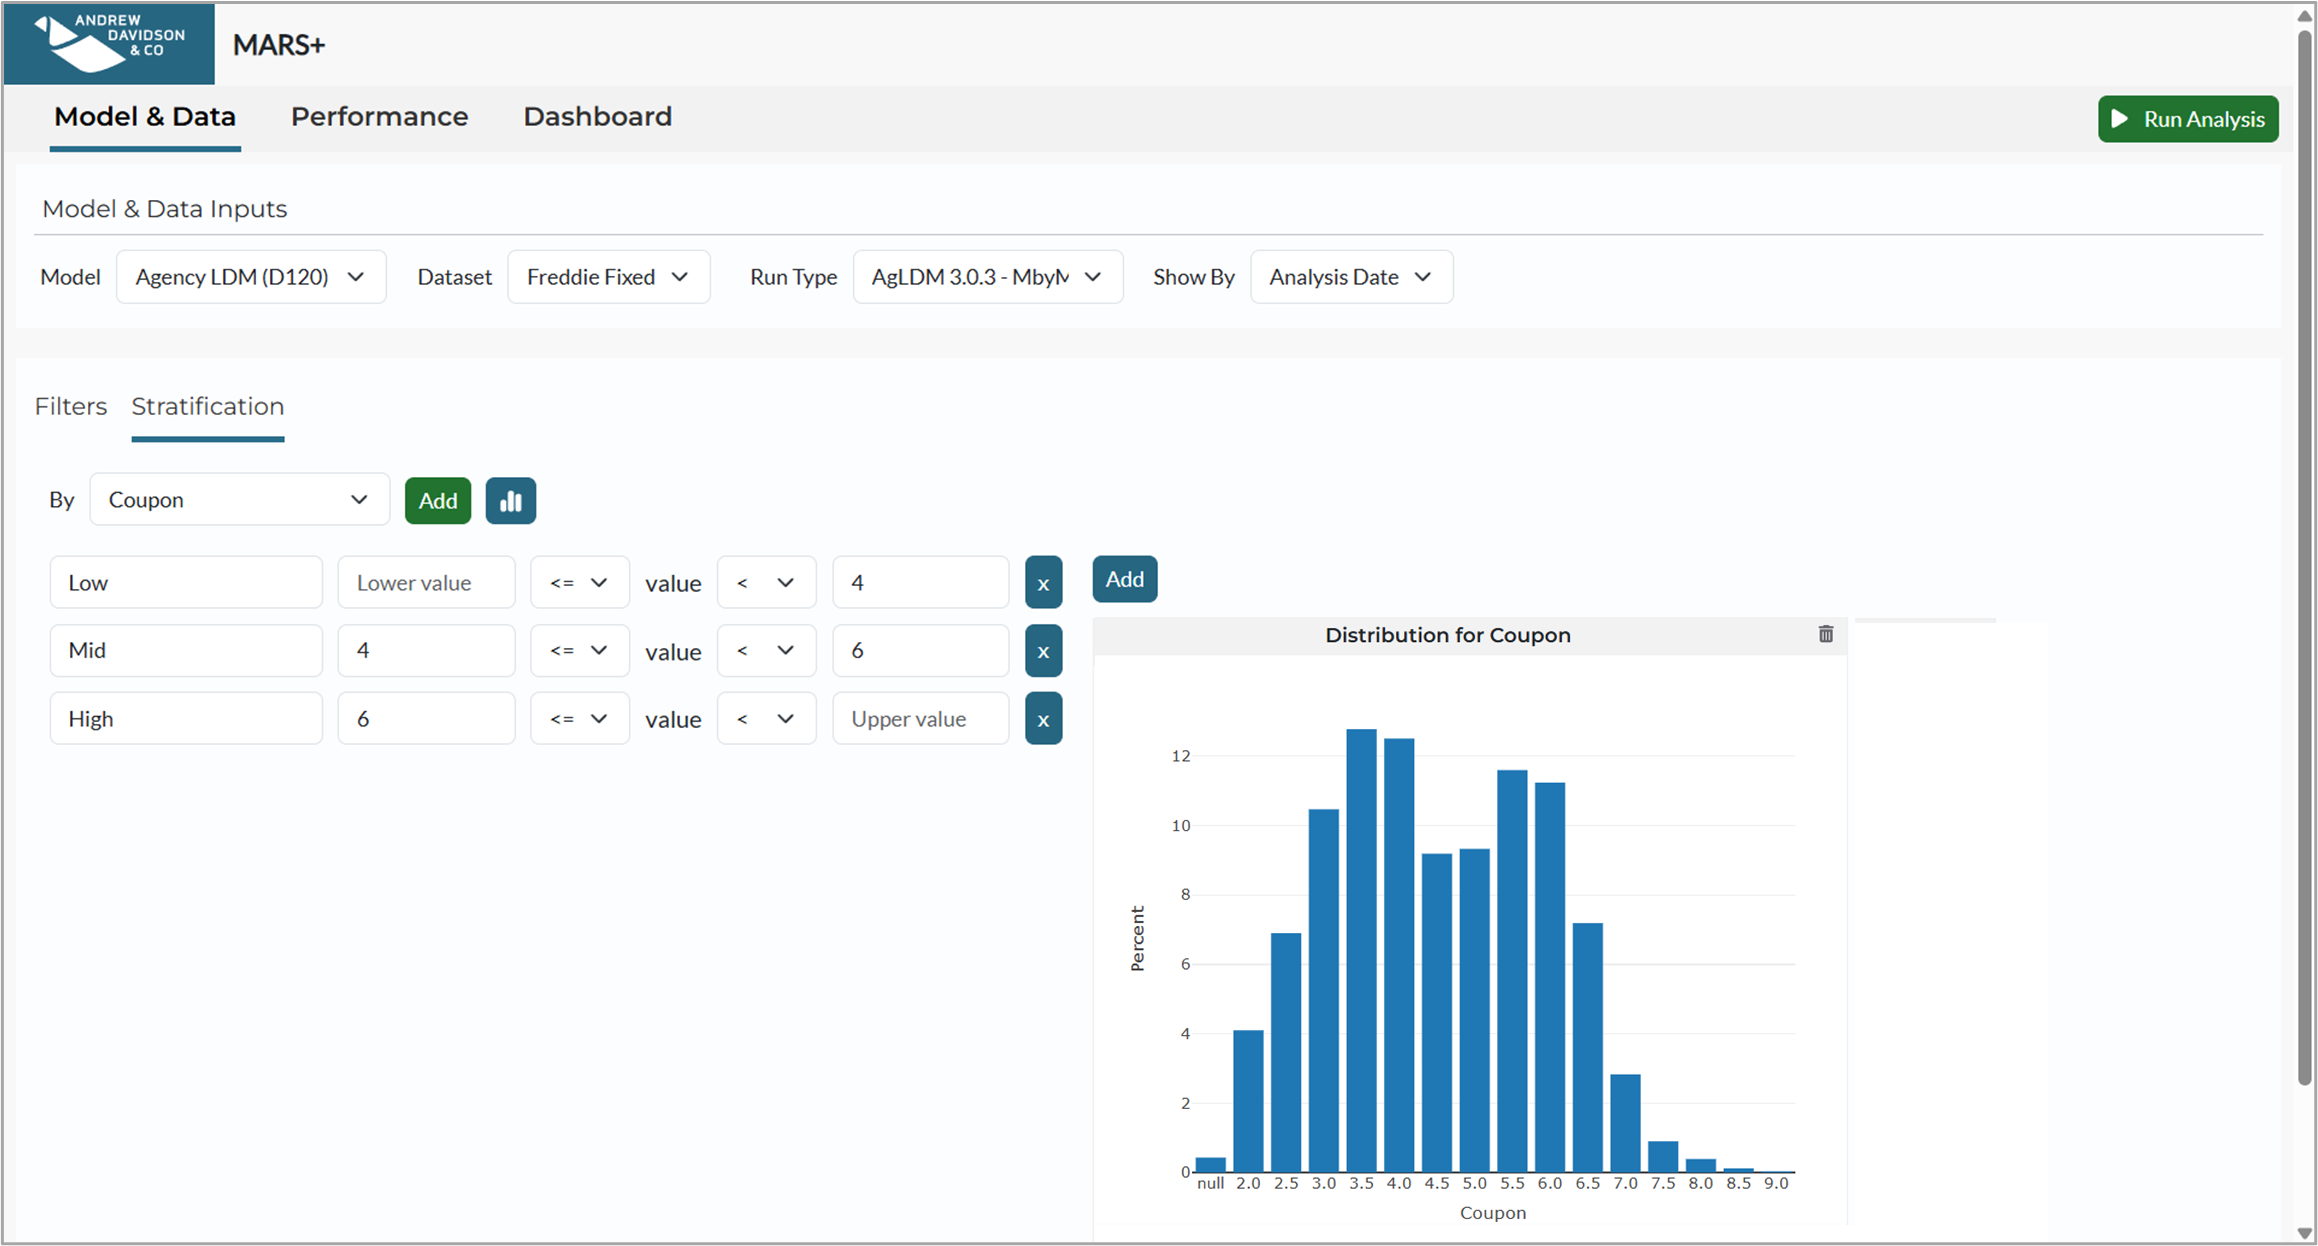
Any distribution chart shown in the ‘Filters’ and ‘Stratification’ panels can also be added to a dashboard to save it for future use, like re-using and continuing the analysis later or for reporting purposes.
Once the data of interest has been defined in ‘Model & Data Inputs,’ ‘Filters,’ and ‘Stratification,’ clicking the ‘Run Analysis’ button will start the retrieval of actual and pre-calculated model data, and display both actual, that is, historical back-testing data and model results for comparison.
Performance Results
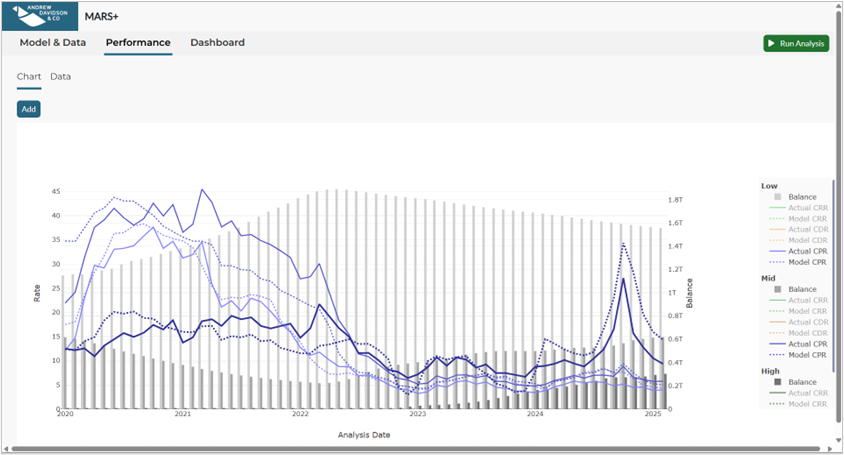
The ‘Performance’ panel displays both actual and model results in an aggregated and stratified form in terms of an interactive chart and a data table as shown in the screenshot below.
While the default chart view typically displays a few parameters, like CPR and Balance, the view parameters can be selected or de-selected from the chart legend.
Any chart or data table viewed in the ‘Performance’ panel can also be added to an existing or a new dashboard to save it for later use.
Dashboard Views
MARS+ provides its users with the facilities to create several dashboards as needed and save them in their local browser’s storage. A dashboard can have up to four components, including user-selected charts and tables generated during the user’s MARS+ session. The following is a sample dashboard with four components that are generated from an analysis run based on selections, filtering, and stratification done in each of the sample screenshots above.
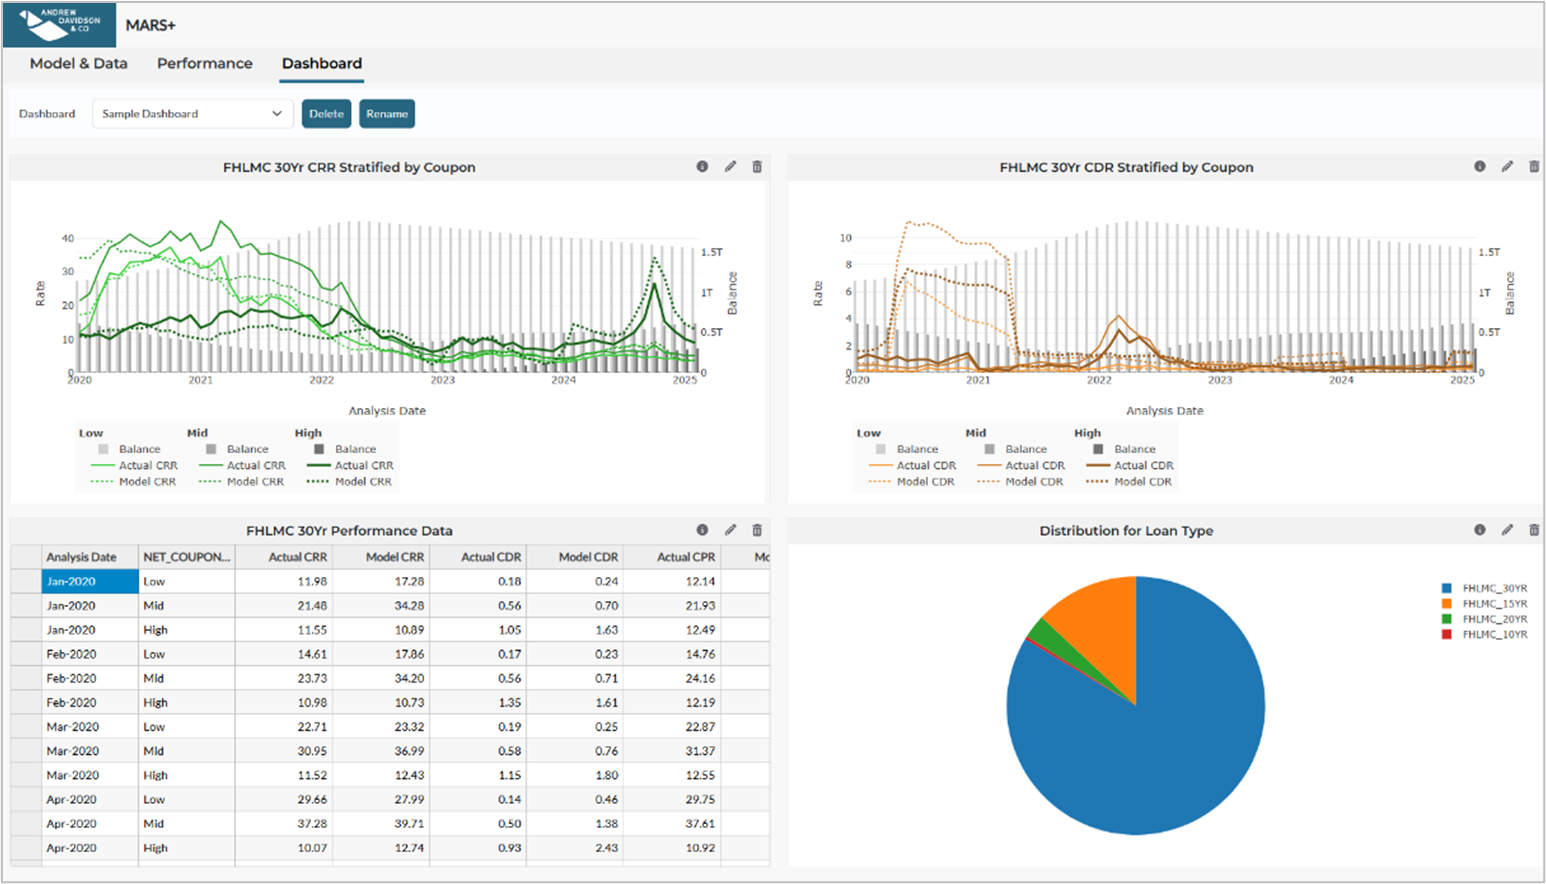
Each dashboard component can also be edited, deleted, or moved within the dashboard.
What is next?
MARS+ will evolve during the beta period in terms of its capabilities, features, and data coverage based on the feedback we receive from our clients and users as ideas, suggestions, questions, issues, and requests. There are also a few planned improvements that we would like to implement during the beta period, including but not limited to:
- Extending the data distributions covering all mortgage data used by our models
- Providing data distribution charts for user-selected dates
- Developing a persistent and secure server-side storage infrastructure enabling users to re-use saved filters, stratifications, and dashboards with original as well as updated data
- Providing additional chart types to display residuals as well as model forecasts beyond the historical back-testing data
Please contact us at support@ad-co.com with any feedback you may have, including your ideas, suggestions, questions, issues, and requests.
The S-Curve Archives
-
 Events
Andrew Davidson & Co., Inc. (AD&Co) held a webinar on June 8th entitled “Lessons Learned: Insights for Managing the Interest Rate Risk of Banks.” Mickey Storms from our Alliances and Policies team, Alex Levin from our Financial Engineering team and Andrew Davidson were featured speakers.
-
 Products
Andrew Davidson & Co., Inc (AD&Co) is pleased to announce the beta release of a new monthly report series titled “Specified Pool Prepayment Trends,” which aims at showing market prepayment trends for specified agency pools in support of pay-up analyses by investors, traders, and alike.
-
 Products
Andrew Davidson & Co., Inc (AD&Co) is pleased to announce that Polypaths LLC supports AD&Co’s Auto LoanDynamics Model (Auto LDM) providing prepayments, defaults and losses on auto loans and securities.
-
 Events
The Structured Finance Association hosted SFVegas 2023 (February 26 - March 1), a broad capital markets conference with thousands of attendees in Las Vegas. Andrew Davidson & Co. Inc. (AD&Co) was a sponsor focused on the mortgage sector. As we engaged with clients and policy leaders, a few themes emerged: Data, Expanding Access Safely, Ginnie Mae Servicing and Auto Loan Performance.
-
 Products
Andrew Davidson & Co., Inc (AD&Co) is pleased to announce the official release of the LoanDynamics Module in Kinetics, AD&Co's new modular platform for running AD&Co analytics via a desktop application, web browser, or REST API. The LoanDynamics Module is the latest way to run the LoanDynamics Model, allowing users to perform sensitivity analysis, validation testing, and scenario analysis in a modern, user-friendly application.
-
 Thoughts
Recently the Federal Housing Finance Agency (FHFA) announced some upcoming changes related to the use of new credit scores, FICO 10T and VantageScore 4.0 by Fannie Mae and Freddie Mac. “FHFA expects that implementation of FICO 10T and VantageScore 4.0 will be a multiyear effort. Once implemented, lenders will be required to deliver both FICO 10T and VantageScore 4.0 credit scores with each loan sold to the Enterprises”.[1] This announcement will impact the entire mortgage ecosystem.
-
 Thoughts
January is National Mentoring Month which is very appropriate since it coincides with the time when we typically set out our goals and intentions for the New Year. Organizations are embracing mentoring programs and these programs have indeed become a strategic imperative for many. There are many benefits to mentorship and it's easy enough to comprehend. The individuals involved in a mentoring relationship and the organizations that choose to sponsor a mentoring program all are likely to benefit.
-
 Thoughts
Homeownership is the largest source of wealth accumulation and inter-generational wealth transfer for the working and middle class. However, the history of racial discrimination (it was actually legal to discriminate by race in housing until the Fair Housing Act of 1968), suggests that we have a continuing responsibility to ensure fair access to housing and housing finance.
-
 Thoughts
Dear Friends,
As Andrew Davidson & Co., Inc. (AD&Co) reaches its 30-year milestone, I reflect on two seemingly contradictory ideas: Firms need experience to guide clients through difficult times but sometimes it is necessary to discard past practices to achieve breakthroughs.
-
 Thoughts
For many people, having accessible transportation (a car, for example) is necessary. Most U.S. people live in areas without adequate public transportation and require vehicles to access jobs, healthcare, and groceries.