
Welcome to The S-Curve
Now you will be able to receive the latest announcements, product updates, and our insights on the mortgage market in real time.
The name of the blog, the S-Curve, is a reflection of our logo and the central feature of our prepayment model. S-curves are seen in nature in many phenomenon, from population growth to prepayment and default models. Our first S-curve, in the early 1990s, used the arctangent function, then piece-wise linear functions, and evolved over time to be more complex and vary by FICO, loan size and LTV. This evolution encapsulates both the timeless nature of fundamental relationships and constant innovation to describe them better over time.
We hope you find the information useful and we look forward to your feedback.
-
 Leveraging Data and Analytics: Highlights from the IMN MSR Forum 2024Events
Andrew Davidson & Co. Inc. (AD&Co) proudly sponsored the Information Management Network (IMN)’s 10th Annual Mortgage Servicing Rights (MSR) Forum, held November 21 - 22, 2024 at the New York Marriott at Brooklyn Bridge. Our servicing expert Richard Cooperstein moderated and I spoke on the panel “Leveraging Trended Data to Enhance Your MSR Portfolio’s Mortgage Prepayment and Credit Modeling.” This panel focused on enhanced consumer data, its impact on delinquencies and prepayments (as shown in our white paper), and the process to bring the data and analytics into decision-making.
Other panels at the event discussed a variety of topics, including the interest rate outlook, macroeconomic factors, climate factors, and their effects on prepayments, escrow, originations, delinquencies, new versus seasoned MSRs, MSR supply and demand, and rate hedging strategies and functionality. The panel discussions underscored the need for a deeper understanding and management of the interest rate and credit risks embedded in the federal mortgage servicing asset. Recapture and the importance of good customer service were recurring themes throughout the conference.
Cautious Optimism for the MSR Market
The overall sentiment regarding MSR assets was a cautious optimism: Despite being a complex asset class, the MSR market remains strong, and people want to buy. Many panelists took the view that due to full employment, a strong GDP, and expectations about the economy and a large and increasing deficit, interest rates in 2025 would see at most a modest decrease before rising again. However, this view was not universally shared, with some pointing to a potential economic downturn and increased defaults being hinted at by delinquency trends in auto credit being close to pre-Covid levels, and the subset of Covid forbearance mortgages that will ultimately default.
For borrowers who already have low mortgage rates, there is limited room for modification; it is interesting to note that one servicer mentioned having some mortgages in foreclosure even with low LTV. Meanwhile, some borrowers bought homes in 2023 hoping to ultimately refinance into lower rates, but the opportunity has not arisen (and might not anytime soon). Finally, due to climate factors and inflation, insurance in some areas is becoming increasingly unaffordable or unavailable. In some regions, such as Florida, some condominium owners are facing massive assessments. One servicer noted that with the current high home prices, most consumers facing high insurance increases can sell their homes. However, there is evidence that when insurance premiums rise to the level of 30-40% of principal and interest, delinquencies also begin to rise. AD&Co’s Climate Impact Suite (currently in beta testing) distinguishes between the effect of climate change on home prices (through Climate Conditioned HPA) and the effect of high premiums on borrower behavior (through Climate Conditioned LDM), with the first effect feeding into the second; if the CLTV remains low, high premiums lead to increased turnover, but if the CLTV becomes high, delinquencies increase.
Uncertainty and the Importance of Prepayment Forecasting
In general, and especially with the new administration coming in, uncertainty was a key theme throughout the forum. It was suggested more than once that the economy may have some curve balls. Regardless – and as always – the ability to forecast prepayment speeds is key for valuing MSR’s. Prepayments determine the total base fee collected on a mortgage, as well as the earnings on escrow and payment float, which have become larger and increasingly important components of MSR valuation due to higher interest rates.
For current coupon mortgages, much depends on the interest rate forecast. For low-rate mortgages, however, it's important to understand the economics of turnover (especially when no rate incentive exists) and predict which borrowers are more likely to prepay at a low rate, such as 3%. The overall low prepayment rate among this set could potentially rise due to a pent-up demand to move, especially with more firms pushing for employees to return to the office.
Many panelists spoke about recapture, which was a prominent theme of the conference: recapture refers to the situation in which the servicer retains the borrower by servicing the new loan as well. Some servicers account for recapture in their valuation, and some use models for predicting recapture rates. The necessity of providing excellent customer service arose in multiple panels as essential for increasing recapture and selling ancillary products while also reducing delinquencies and defaults.
"Know Your Data and Your Portfolio"
One panelist observed that, in the current environment, it is now more important than ever for servicers to “know your data and your portfolio”. The topic was addressed during the AD&Co-moderated panel “Leveraging Trended Data to Enhance Your MSR Portfolio’s Mortgage Prepayment and Credit Modeling”. David Doyle of Sagent first discussed some of the challenges in understanding the strengths and risks of potential MSR acquisitions, while Gauhar Turmuhambetova of BlackRock outlined the challenges of using dynamic credit bureau data in the valuation of securitized products. Bindiya Jain of Experian described the granular loan-level insights available on their platform and specifically within their mortgage performance dataset. Then I shared research that illustrates how Experian’s trended data attributes may be used to improve mortgage prepayment and delinquency forecasts beyond what may be inferred from a traditional credit score. I also demonstrated through AD&Co’s MSRKinetics application how these improved forecasts would affect the base fee and cost components of MSR valuation for sample GSE and FHA loans, as well as their weighted average lifetimes and duration profiles.
Overall, IMN’s MSR forum provided a rich opportunity to engage with participants in the MSR industry, learn about their views and needs, and explore potential synergies.
-
 AD&Conversations: AD&Co Updates its Home Price Index ModelPodcast
Tune in to Michelle Stepien Breier's interview with Alex Levin & Matteo Caracciolo-King as they discuss their latest Pipeline article “AD&Co Updates its Home Price Index Model.” The interview highlights key points from the article as they share recent updates to the HPI3 model. If you’re intrigued and eager to learn more, hit play or click the link to read the full article!
Login is required to access this Pipeline article.
-
 Revisiting the Capital Treatment of Credit Risk TransferThoughts
With the increasing volumes of Synthetic Risk Transfer (SRT) and Credit Risk Transfer (CRT) along with the discussion of BASEL III, we thought it would be useful to re-issue our comment letter to FHFA on the capital treatment of Credit Risk Transfer.
CRT is not quite the same as either equity or debt from a capital perspective; however, capital rules often attempt to categorize them this way and then add ad hoc adjustments. Our comment letter addressed an appropriate framework for understanding the risk reduction impact of CRT transactions.
-
 Panoramic Capital Podcast: Prepayment Modeling with Daniel SwansonPodcast
Recently, senior credit modeler, Daniel Swanson had the pleasure of speaking with Rob Kessel from the Panoramic Capital Academy podcast titled, “Modeler’s Perspective on Prepayment Modeling.” This podcast is part of the curriculum in Panoramic Capital Academy's capital market course, an accredited 14-week class for capital market professionals, including hedging mortgage pipelines and valuing mortgage servicing rights (MSRs). The discussion covered topics like data gathering, how to forecast speeds in an ever-changing world, validating results and how modeling evolved to include more loan-specific variables.
Click here to listen.
About Panoramic Capital Academy and Consulting
Panoramic Capital Academy and Consulting offers an advanced mortgage capital markets training program, providing accessible and foundational education to the mortgage industry to accelerate careers, improve financial performance, and foster respect in the industry. Panoramic also provides mortgage capital market consulting services.
More information can be found at www.panoramiccap.com.
-
 Real World Data on House Price Impact of Climate RisksThoughts
The earliest paper we found examining the impact of climate risks on house prices was from 2017, which found a relationship between elevation/sea level rise and house price differences.[1]
We built our climate-conditioned HPA model in 2022 based on the idea that an increase in insurance costs would impact house prices (something we had not studied yet) in the same way that an increase of the same size in mortgage rates would impact house prices (something that we were quite familiar with).
The real world evidence for this relationship has been accumulating recently – on October 15, 2024 the Washington Post published an article entitled “Where climate change poses the most and least risk to American homeowners” which contains the following chart (which is based on an analysis of 2 million home sales in Florida since 2000):
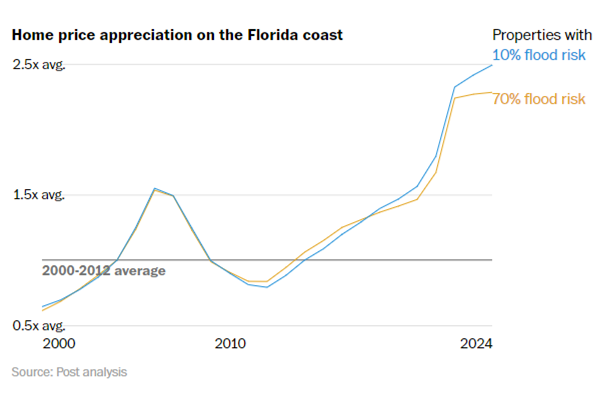
We can see from the lines comparing lower and higher flood risk properties that until very recently, the housing market was not pricing for flood risk. But now there is a clear divergence in price trend.
For the particular case of Florida, there is reason to believe that this trend will strengthen in the near term: until recently, the only reason most people got flood insurance was that they were in a FEMA flood zone and they were required to buy a NFIP policy in order to obtain a mortgage. FEMA flood zone maps are known to be extremely outdated. However, with the accumulation of flooding incidents occurring outside those zones and the publishing of flood risk scores on Zillow, buyers are becoming much more aware of flood risk whether or not a property is in a FEMA zone.
Additionally, the state of Florida is gradually requiring all homeowners buying insurance through Citizens (its FAIR plan for homeowner’s insurance) to also have flood insurance regardless of flood zone status. This requirement started in 2024 for houses priced $600,000 and above, and by January 1, 2027, will extend to all properties insured by Citizens. At the end of 2023, Citizens was the largest insurer in Florida with 15% of all policies and over half a trillion dollars of insured properties.
Furthermore, the different post-event experiences of homeowners who have flood insurance versus those who didn’t is likely to encourage more homeowners – even those not taking a policy through Citizens – to add flood insurance to their property. So flood risk, at least in Florida, is getting closer to being fully priced into real estate values.
While the Washington Post article only discusses flood risk, all borrower costs matter to housing affordability – property taxes, homeowner’s and flood insurance, and the mortgage (leaving aside the psychological costs of nuisance events that don’t rise to the level of filing a claim). To truly capture the potential impact on both house prices and borrower behavior of all these rising costs, a fully climate conditioned approach, combining home prices as well as borrower behavior models (how will prepayment, delinquency, default and loss severity be affected?) is required. This is what our Climate Impact Suite offers.
[1] https://papers.ssrn.com/sol3/papers.cfm?abstract_id=3073842&itid=lk_inline_enhanced-template
The S-Curve Archives
-
Thoughts
As interest rates rise and fewer loans with refinancing incentive remain, other factors are primed to play a larger role in determining prepayment speeds in the coming months (and perhaps years). Turnover, the rate at which people move, is the most cited of these factors. In this blog post, we’ll consider two other potential drivers: curtailments, or partial prepayments, and mortgage payoffs that don’t involve taking out a new loan.
-
Thoughts
Summary
In 2021, Andrew Davidson & Co. Inc. (AD&Co) proposed a benchmark cohort approach to setting Ability-to-Repay (ATR) Qualified Mortgages (QM) standards. Successful benchmarks based on data are model-free and transparent, and the cohorts must perform consistently in comparison to one another and across time. Our original work used data through the early stages of the pandemic when non-performing loan percentages skyrocketed.
-
 Thoughts
How Lowering Capital Costs Affects Higher-Risk Loans
Government-sponsored enterprises (or GSEs) are companies that provide guarantees and financing to originators through the mortgage secondary market. The size and resilience of the GSE secondary market maximizes diversification and liquidity which reduces financial risk and cost of capital. This benefit accrues to conforming borrowers through lower mortgage rates and resiliently available financing.
-
 Products
The release of Andrew Davidson & Co., Inc.’s (AD&Co) new generation of financial engineering tools marks a shift to a new reality; when the traditional benchmark for MBS valuation, the LIBOR/ Swap yield curve, becomes unavailable. Our recent Product Release email informed our readers about the change. In short, our users can:
-
 Thoughts
FHFA held a listening session for interested parties on its proposed rule on the GSE process for credit scores. The objective is making mortgage underwriting and pricing more accurate and more fair while balancing practical implementation by firms in the mortgage ecosystem. Along with many others, I had the opportunity to provide insights on this proposed rulemaking.
-
 Thoughts
In our January 19th blog entitled, A More Equitable Lending System Will Not Be Created by Accident, we described the efforts it will take to overcome not just bias in lending today, but the systemic factors that have limited access to credit in the past and have created an unjust system.
-
 Thoughts
In this short blog post I discuss some developments taking place in the flood insurance landscape in the US and look ahead at a few potential directions things could go. I suggest that universal catastrophic flood insurance coverage with a continuation of the introduction of risk-based pricing would be a significant improvement.
-
 Thoughts
Introduction
The Government-Sponsored Enterprises (GSEs) entered conservatorship in September 2008. One could view the succeeding thirteen years as a journey back to financial stability with a refined operating model that looks more like a financial utility than a hedge fund. This business model is more compatible with a fair lending mission for a standard-setter that maintains secondary markets under an effective regulator. The GSEs remain the largest part of the housing finance backbone and a resilient funding source during economic stress.
-
Thoughts
Around 75% of white American families were homeowners in the first quarter of 2020, according to data from the United States Census Bureau. However, only 44% of Black American families owned their homes at the same time.
-
Thoughts
According to a report by the Research Institute for Housing America, climate change risk is rapidly increasing in the housing industry and will continue to demand more attention and regulation in the near future.