
Welcome to The S-Curve
Now you will be able to receive the latest announcements, product updates, and our insights on the mortgage market in real time.
The name of the blog, the S-Curve, is a reflection of our logo and the central feature of our prepayment model. S-curves are seen in nature in many phenomenon, from population growth to prepayment and default models. Our first S-curve, in the early 1990s, used the arctangent function, then piece-wise linear functions, and evolved over time to be more complex and vary by FICO, loan size and LTV. This evolution encapsulates both the timeless nature of fundamental relationships and constant innovation to describe them better over time.
We hope you find the information useful and we look forward to your feedback.
-
Andrew Davidson & Co., Inc. Celebrates Pride MonthEvents
We at Andrew Davidson & Co., Inc. (AD&Co) are once again thrilled to celebrate Pride Month, especially the contributions of LGBTQ professionals in the field of finance including affordable housing policy and the GSEs. This year, in addition to celebrating, we are also paying increased attention to the challenges that LGBTQ individuals face, particularly around issues of housing. Our pride in our LGBTQ staff and community sits alongside our concern about discriminatory lending practices, including in mortgages. As of February 2021, for the first time, lesbian, gay, bisexual, transgender, queer, and questioning (LGBTQ) Americans will be protected from housing discrimination under the Fair Housing Act.
We have also had our eyes opened to youth homelessness. LGBTQ people make up 40% of the homeless youth population in the country: Their risk of homelessness is 120% of the general population.
We at AD&Co are committed to change. Here’s to Pride!
-
U.S. Mortgage High Yield Indexes From Andrew Davidson & Co Added to St. Louis Fed's FRED DatabaseNews
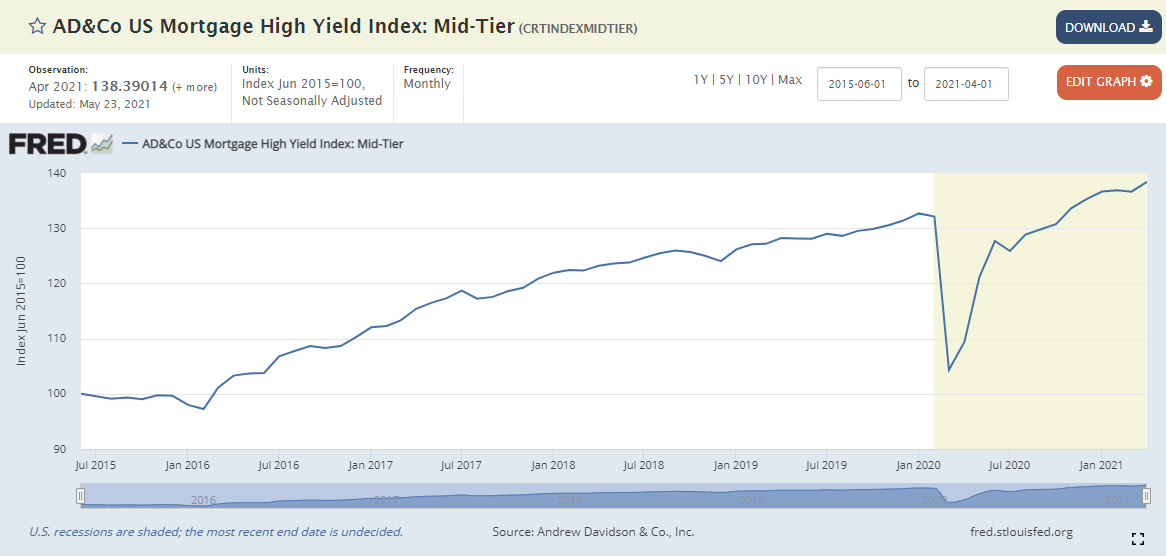
For several years, AD&Co has tracked the total rate of return (TRR) performance of the GSE CAS and STACR CRT in its U.S. Mortgage High-Yield Indices. The AD&Co Mid-Tier index constitutes a broad market measure of the TRR performance of GSE CRT. The related sub-indices segregate the CRT market into 4 index Tiers by attachment point, reflective of the credit exposure of the various classes of underlying CRT ranging from B to M1.
We are pleased to announce that the historical time series for these indices is now publicly available on the St. Louis Federal Reserve's FRED database, along with the credit-adjusted OAS (CrOAS) for each series. FRED is host to almost 800,000 data series from more than 100 sources. The indices published on FRED can be viewed here. Detailed performance analysis related to the index is available on a monthly basis at through AD&Co.
For more information please contact Rob Landauer at 212-274-9075, email Rob at rob@ad-co.com or visit www.ad-co.com.
Disclaimer: The AD&Co U.S. Mortgage High-Yield Index serves as an informational index and is not for commercial-use purposes. The Index’s accuracy, completeness, timeliness, and suitability for any purpose are not guaranteed. The Index does not constitute (1) investment, legal, accounting, tax, or other professional advice or (2) any recommendation or solicitation to purchase, hold, sell, or otherwise deal in any investment. This Index has been prepared for general informational purposes, without consideration of the circumstances or objectives of any particular investor. Any reliance on the Index is at the reader’s sole risk. All investment is subject to numerous risks, known and unknown. Past performance is no guarantee of future results. For investment advice, seek a qualified investment professional. Not for redistribution without permission. Note: An affiliate of Andrew Davidson & Co., Inc. engages in trading activities in investments that may be the same or similar to those featured in the Index.
-
Asian Pacific Heritage MonthEvents
We at Andrew Davidson & Co., Inc. (AD&Co) stand in solidarity with the Asian community and speak out against the xenophobic ignorance that has led to increased racist attacks against Asians. We protest against these hate crimes. This is a time to celebrate the richness that we have gained from the diversity of the Asian culture. We pledge to support the heritage that is part of what makes us American.
-
Mental Health Awareness MonthEvents
What does it mean to be mentally healthy? The answer is different for everyone. With all the extra anxiety that many of us have experienced since 2020, whether from uncertainty about COVID-19 or from other experiences that may be new to us, it’s important to acknowledge that it’s alright to not feel alright. Fortunately, there are numerous resources that are available locally, nationally, and in some cases through your workplace or benefits package. We might start by finding out what makes us feel better. For some, it is a brisk walk outside, a yoga class, talking to a friend, or finding a sympathetic therapist. The possibilities are endless. Let’s take this month to think about what WE need.
-
Introducing AutoLDM—A New Way to Analyze Auto LoansProducts
Today marks the publication of Chris Widman's Quantitative Perspective, a comprehensive article on the newest member of our LoanDynamics suite, the Auto LoanDynamics Model. Auto LDM will be integrated into vendor systems and AD&Co tools, allowing users to perform analysis on auto loan and ABS positions. Applications include economic scenario analysis to examine the impact of unemployment scenarios or rates on defaults, losses and prepayments, stress testing for CCAR/CECL, valuation and risk measurement.
The article provides an overview of the auto loan market, discusses the underlying data used for estimation, our model architecture, and contains sections on delinquency, seasonality, unemployment and severity determinants. We look forward to your feedback – please reach out to us at support@ad-co.com if you are interested in more details or a trial.
-Eknath Belbase
The S-Curve Archives
-
 Thoughts
Financial institutions rely on models for a wide range of purposes, including valuation, forecasting, risk management, capital planning, accounting, trading, and reporting. The same model may be used differently by different organizations, and sometimes differently within the same organization. For that reason, model validation should not begin with the question, “Is the model correct?” Instead, the more useful question is: “Is the model appropriate for the purpose for which it is being used?”
-
 Thoughts
Over the past summer, Andrew Davidson & Co., Inc. (AD&Co) was pleased to have Stephanie Duenas and Anika Chatterjee interning with us at our office in New York City. During this time, Stephanie and Anika performed a detailed analysis of mortgage performance data to consider the question of whether and how two credit scores, when available, could provide lift over a single score in predicting mortgage delinquencies.
-
 Events
AD&Co in Action: Volunteer & Cultural Days 2026
At Andrew Davidson & Co., Inc. (AD&Co), our values extend beyond the work we do for our clients. Humanity, inclusivity, dedication, citizenship, creativity, and integrity shape how we engage with one another and with our community. This August, members of the AD&Co team took the opportunity to put those values into practice during our Volunteer Day supporting Volunteers of America-Greater New York’s Operation Backpack® and our Cultural Day at Ellis Island.
-
 Thoughts
Recently, aggregators have crossed market borders by issuing residential mortgage-backed securities (RMBS) backed by owner-occupied (OO), GSE-eligible conforming loans. Additionally, conforming mortgage loans have drawn investment interest from insurance companies fronted by aggregators and evaluated by third-party firms. These developments constitute historically rare disintermediations of the nearly monopsonist purchases of conforming loans by the GSEs.
-
 Podcast
Join Rob Landauer in a conversation with Abe Martin as they discuss his recent Pipeline article, "Modeling the Balance Behavior of HELOC Borrowers." In this episode, they highlight key points from the article as he shares insights into the draw component of HELOCs and provide an update on the beta rele
-
News
We’re excited to announce a major addition to the Andrew Davidson & Co., Inc. (AD&Co) team. Industry leaders Kelli Sayres and Gene Park, known for building and scaling leading fixed-income analytics platforms, have joined AD&Co’s Business Development team.
-
 Thoughts
Building on our earlier research on expanded consumer attributes, AD&Co continues to explore how credit data contributes to modeling delinquency and prepayment risk, which are key drivers of mortgage servicing rights cash flows and valuation.
-
 Events
Andrew Davidson recently joined NFM Lending’s Greg Sher on the One On One podcast to discuss our recent white paper, “The Impact of Moving Away From the Tri-Merge Standard.”
-
 Events
AD&Co recently sponsored and attended SFVegas 2026 and Optimal Blue Summit 2026. This post shares the AD&Co team's unique perspectives and key takeaways from attending both conferences.
-
 News
AD&Co US Mortgage High Yield Indices
The Federal Reserve Economic Data (FRED) portal, housed by the Federal Reserve Bank of St. Louis, has been publishing AD&Co’s CRT indices since 2019. These series posted under the overall name of “US Mortgage High-Yield” include total return rates and credit and option-adjusted spreads (crOAS) – a projected return’s spread over Treasury (in the past, Libor). These series are available going back to 2014-end and tiered by CRT initial supports.